
Credit Acceptance’s warehouse renewal: collateral governs borrowing
Credit Acceptance’s Warehouse II renewal leaves collateral and collections tests governing advances and principal payments throughout the revolving period.
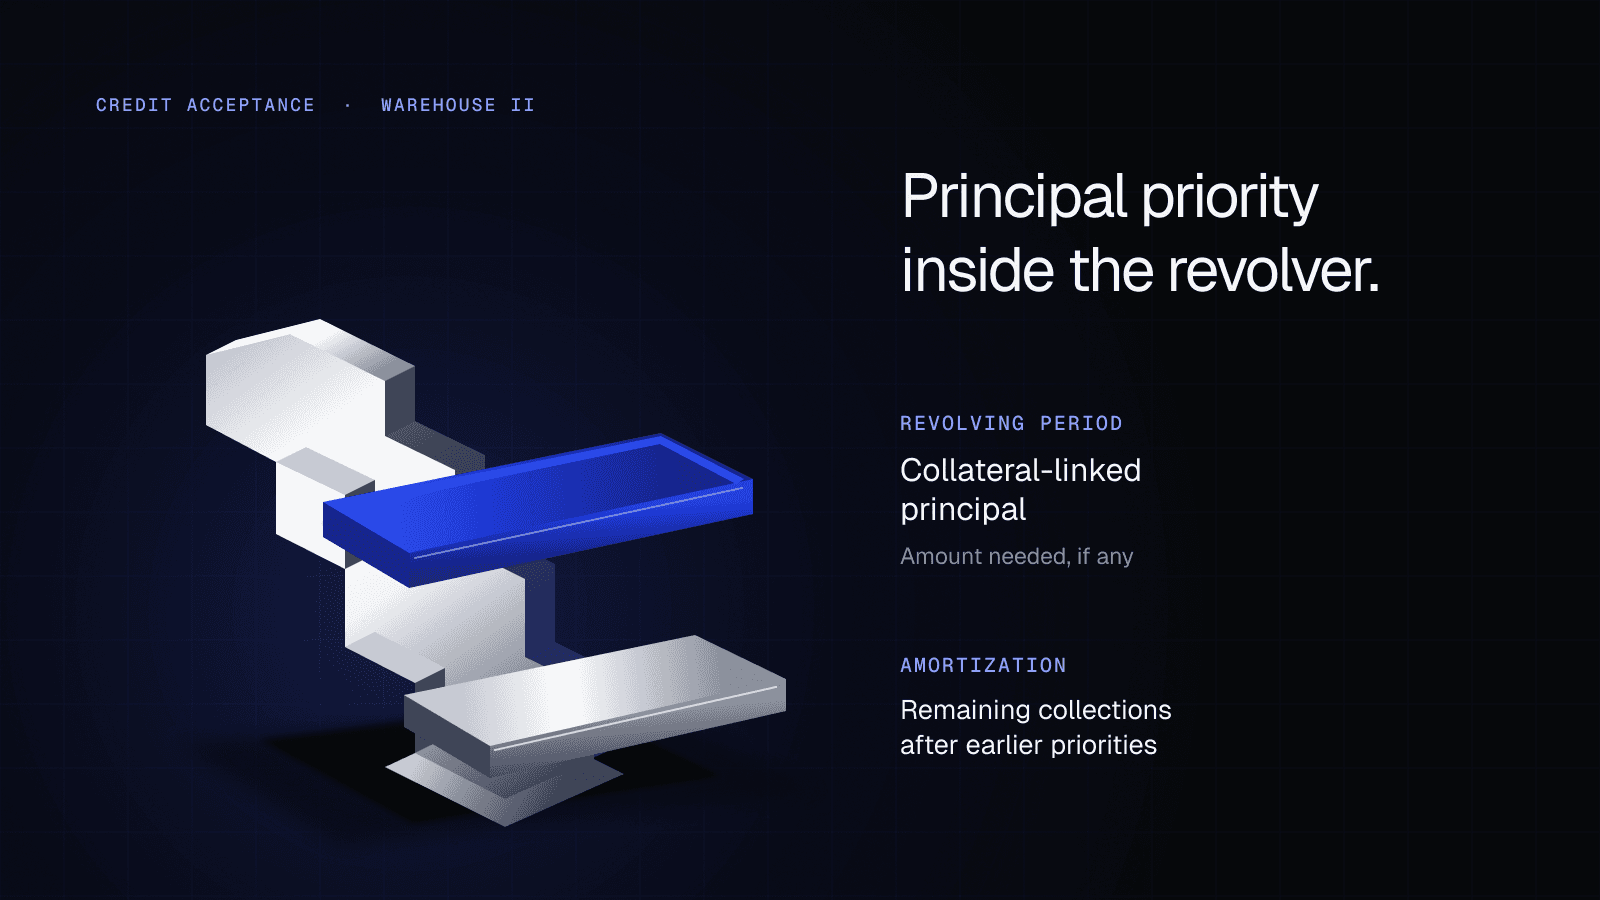
Credit Acceptance’s Warehouse Facility II can require principal reduction while it remains open for further advances. In the filed loan agreement, the payment waterfall directs a monthly principal amount to lenders during the revolving period when an amount is needed to bring outstanding Capital back to the borrowing base. For an originator’s treasury team, eligible collateral and the collections forecast therefore matter to liquidity planning throughout the facility’s life.
The September 15, 2026 announcement extended the existing USD 500 million warehouse’s scheduled revolving end from September 20, 2027 to September 15, 2028. Its borrowing spread fell from SOFR plus 185 basis points to 175 basis points. Credit Acceptance reported USD 180 million outstanding on September 15. The current report filed September 21 gives the same dated balance; it does not establish current borrowing availability.
Supported borrowing depends on two collateral tests
Section 2.1 caps an advance so that aggregate outstanding Capital stays within the lower of the facility limit and the borrowing base. The base itself is the lower of two calculations. One applies the Net Advance Rate to eligible loan balances after the concentration adjustment, then adds Excess Reserve Amounts. The other uses 65% of Forecasted Collections, plus Excess Reserve Amounts divided by 0.65.
The marked amendment replaces 60% with 65% in the forecast limb and changes its reserve divisor from 0.60 to 0.65. The higher forecast multiplier alone cannot quantify additional borrowing room: the reserve conversion changes alongside it, and the eligible-loan calculation can still be the binding test. Applying 65% to the facility limit or to all originated loans would miss the contractual measurement base.
Forecasted Collections is a defined model output. Credit Acceptance determines expected collections on the eligible loan balance using its forecasting model and submits the forecast to the deal agent with a funding notice when new pools are pledged. Section 3.2 also requires forecasted collections after a proposed advance to be at least outstanding Capital after that advance, alongside the other funding conditions. A forecast can support the lending calculation before those collections arrive as cash.
Principal already has a place in the revolving waterfall
The agreement defines the Monthly Principal Payment Amount as the amount, if any, needed to reduce Capital to the borrowing base. Section 2.7(a)(v) puts that payment fifth in the revolving-period waterfall. Earlier priorities include hedging costs, servicing obligations and lender yield and fees.
That priority gives collateral deterioration a potential liquidity consequence before scheduled amortization begins. If the borrowing base falls below outstanding Capital, the defined principal amount increases to cover the gap. If no reduction is necessary, that definition does not create a fixed monthly principal installment. The allocation operates through the specified available funds and collection-account amounts in their contractual order; it is not a promise that every gross collection goes to principal.
For a treasury forecast, the relevant variables consequently include which loans remain eligible, the concentration adjustment, modelled collections and reserve balances. A long remaining revolving period and a lower interest spread do not hold those inputs constant. The public amendment supplies the mechanism, without the current collateral tape, model forecast or certificate needed to diagnose an actual deficiency or compliance position.
Amortization changes the collection allocation
During the amortization period, the waterfall’s seventh priority pays the Additional Principal Payment Amount until Capital is reduced to zero. That amount is the lower of the preceding payment date’s Capital, after its principal payments, and collections remaining after the first six priorities. Earlier amortization or termination events also stop further funding; the announced September 2028 revolving end is not an unconditional draw commitment or a final bullet-repayment date.
Altss’s comparison of originator financing and other private-credit mandates identifies the asset originator as a distinct recipient of capital. Warehouse II shows why the financing contract matters within that category. Collections enter both the forecast supporting borrowing and the allocation that returns principal to lenders. Extending the revolving period preserves time to finance qualifying assets, while collateral support and the cash waterfall continue to govern how much lender capital can remain deployed.