Framework · Version 1.2.0 · Last reviewed
Source check: Legal and regulatory statements checked against the cited primary sources on (how). General information, not advice.
Institutional LP Manager Due Diligence Framework
A method for LPs to evaluate a private-fund manager before committing: investment due diligence across ten domains, evidence and verification rules, finding severity and decision outcomes, mapping to ILPA DDQ 2.0 and the AIMA DDQ, an operational due diligence gate and a family-office variant.
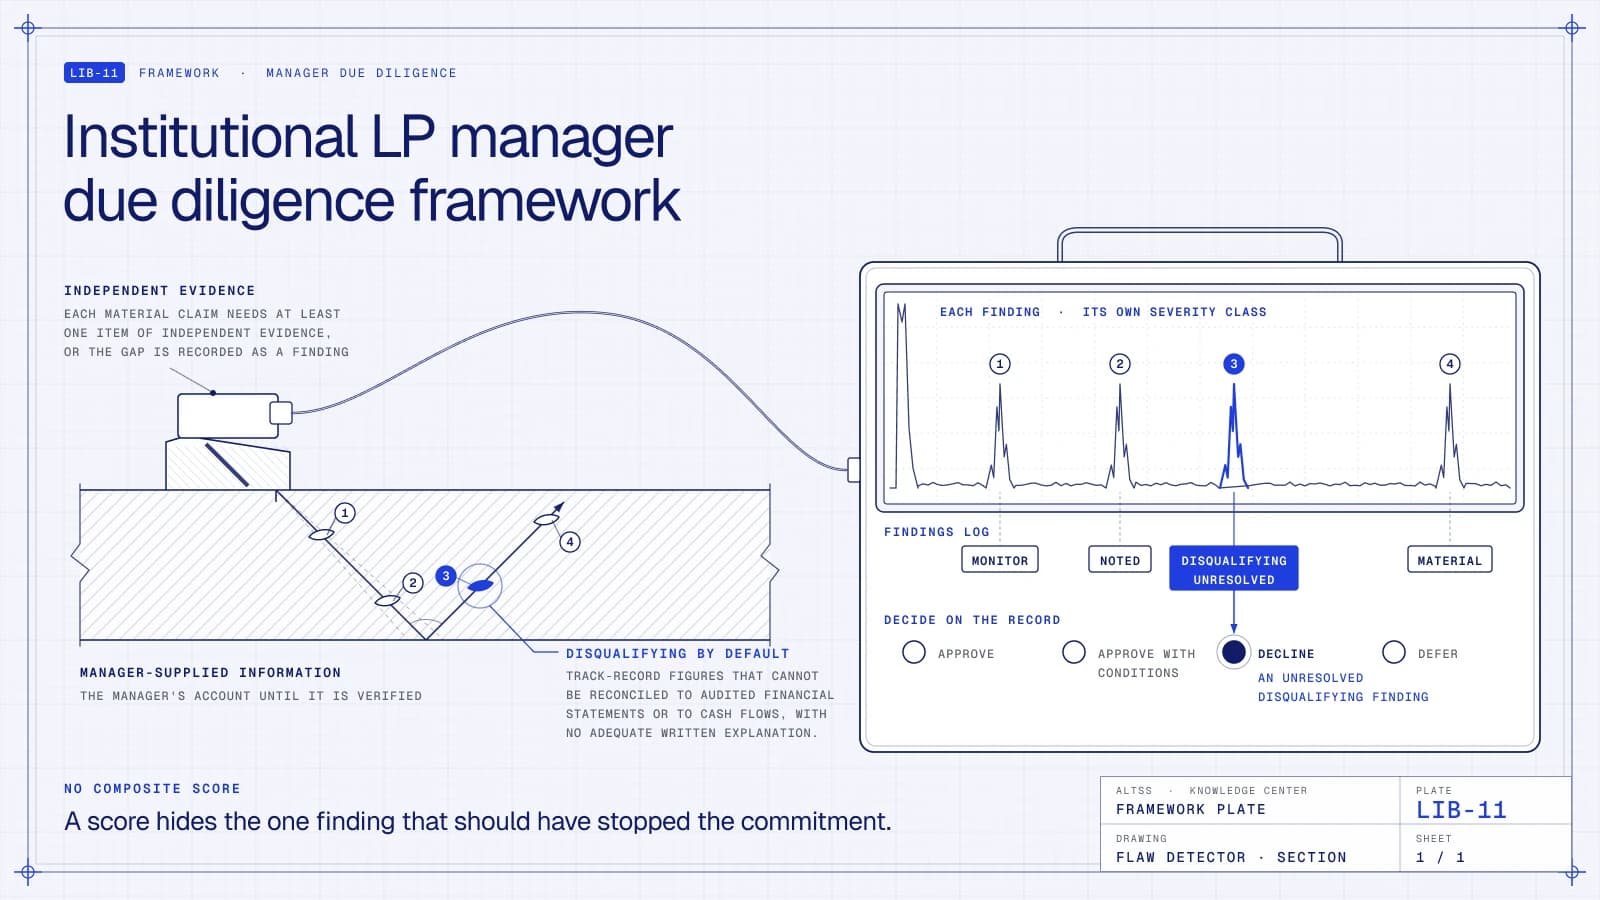
Reference plate: findings are classified on the record, with no composite score.
1. Purpose
This framework sets out how a limited partner evaluates an investment manager and a specific fund before committing capital, and how it records that evaluation so that an investment committee, an auditor or a successor can see what was checked, against what evidence, and with what result. It covers investment due diligence and manager evaluation in full. It sets the minimum gate for operational due diligence, which has its own framework.
It has two readers. An LP uses it as a procedure: what to request, what to verify independently, how to classify what it finds and how to reach a documented decision. A manager uses it to see what a disciplined LP will ask for and what it will check. The framework does not say whether to invest. It describes how to reach that decision and how to show the work.
It replaces two earlier pages, a general LP checklist and a separate family-office diligence process. The family-office material is now a variant of the same method (section 8). The evidence a family office needs about a manager is the same as an institution's; what differs is who decides, how much in-house capacity exists, and some eligibility and reporting questions.
2. Scope
In scope
- Primary commitments to closed-end private funds: buyout, growth, venture, private credit, real estate and infrastructure funds.
- Re-ups to a successor fund of an existing manager.
- Emerging and first-time managers, with the additional evidence questions in section 12.
- Open-ended and evergreen private funds and hedge funds, with the adjustments noted in sections 7 and 12.
- Diligence carried out by family offices (section 8).
Out of scope, and where it is covered
- The operational due diligence procedure: Operational Due Diligence Framework. This framework sets only the gate (rule 5.9).
- Detailed review of fund terms: Fund Terms & Alignment Framework.
- Performance calculation conventions: Private Markets Performance Measurement Standard. Peer groups and public market equivalents in depth: Private Markets Benchmarking Methodology.
- Track record attribution in depth: Track Record Attribution & Quality Framework.
- Valuation policy and mark quality: Private Capital Valuation & Mark Quality Framework.
- Continuation vehicles and other GP-led transactions: Secondaries & Continuation Vehicle Evaluation Framework.
- Portfolio fit, pacing and sizing: Commitment Pacing & Liquidity Framework and LP Portfolio Construction Framework.
- How an institution's committee reaches an allocation decision: How Institutional LPs Make Allocation Decisions. What family offices look for in a manager: Family Office Investment Criteria Guide.
- Legal, tax and regulatory advice. Where this framework refers to a rule, it states what the rule says. Applying it to a particular investor or manager is a matter for their counsel.
3. Definitions
- Due diligence. The investigation an investor carries out before committing, to establish the facts on which the decision rests. See due diligence.
- Investment due diligence (IDD). Evaluation of the firm, strategy, team, process, track record and terms: whether the manager can produce the returns it targets, and whether the LP shares in them on fair terms. See investment due diligence.
- Operational due diligence (ODD). Evaluation of the controls, service providers, infrastructure and governance that protect the LP's capital and the accuracy of what the manager reports. See operational due diligence.
- DDQ. A structured questionnaire the manager completes. Standard forms include the ILPA Due Diligence Questionnaire 2.0 and the AIMA illustrative questionnaires. See due diligence questionnaire.
- Data room. The repository of documents the manager makes available during diligence. See data room.
- Offering documents. The private placement memorandum, the draft limited partnership agreement, the subscription agreement and any side letter.
- Fund family and predecessor funds. The manager's earlier funds in the same strategy. Their results make up the fund-level track record.
- Attributable track record. The part of a track record for which the people who will manage the new fund were responsible. See track record attribution.
- Key person. An individual named in the LPA whose departure or reduced involvement triggers the key person clause. See also key person risk.
- Manager-supplied information. Anything produced by the manager or on its behalf, including DDQ answers, pitch materials, track-record schedules, and data-room documents the manager prepared. Material prepared by a placement agent for the manager is manager-supplied.
- Independent evidence. Evidence whose origin is not the manager: an auditor's opinion, a regulator's or court's record, a counterparty's own statement, a reference the LP found itself.
- Back-channel reference. A reference the LP identifies and contacts itself, rather than one the manager supplies.
- Material claim. A statement by the manager that would change the decision if it were false.
- Finding. A recorded observation that bears on the decision, with its evidence, its date and its severity class (rule 6.1).
- IC memo. The document that sets out the recommendation and findings for the decision-maker. See investment committee memo.
- Emerging manager. A manager early in its fund history. LPs define the term differently (by fund number, firm assets or years of operation), so the definition used is recorded. See emerging manager.
4. Inputs and source types
4.1 Inputs
| Input | Whose account it is | Used for |
|---|---|---|
| Pitch book and PPM | The manager (marketing and disclosure) | Hypotheses to test. Never evidence of results on its own. |
| DDQ and exhibits | The manager | Coverage, and a written record of what the manager stated. |
| Track-record schedules: fund-level performance and cash flows, deal-level data | The manager | Reconstructing returns (rule 5.5). |
| Audited financial statements of predecessor funds | The manager's statements, with an independent auditor's opinion | The anchor for reconciling track record, NAV and capital accounts. |
| Quarterly reports and capital account statements, including the ILPA Reporting Template and ILPA Performance Template where used | The manager or its fund administrator | Reconciling fees, expenses, carry and performance; judging reporting quality. |
| Draft LPA, side letter terms, subscription documents | The manager's counsel | Terms and legal review. |
| Policies: valuation, compliance manual, conflicts, business continuity, cybersecurity, responsible investment | The manager | ODD and governance review. |
| Regulatory records, for US advisers Form ADV through the SEC's Investment Adviser Public Disclosure site; other regulators' registers elsewhere | Filed by the manager under a legal duty | Registration status, regulatory assets under management, disclosed disciplinary history, private funds advised. |
| Court records, enforcement records, sanctions lists | Public bodies | Litigation, enforcement and sanctions screening. |
| References: LPs, portfolio company executives, co-investors, former employees, service providers | Third parties | Conduct under stress, consistency with the manager's account. |
| Meetings and on-site visits | The LP's own observation | Team dynamics; inspecting original documents. |
| Commercial datasets and peer data | Licensed third parties | Locating information and peer comparison. Not on their own evidence of a manager's results. |
4.2 Rules on inputs
- Every document is recorded with its title, version, the date received and the as-of date of its contents.
- Manager-supplied information is the manager's account until it is verified. Its presence in a data room does not verify it.
- A regulatory filing is the filer's statement, made under a legal duty and in a prescribed form. It is not a regulator's finding. The SEC states that by accepting a Form ADV it does not make a finding that the form was completed or submitted correctly.
- An auditor's opinion covers the financial statements it accompanies, at their date. It does not cover performance figures in marketing materials, even when they are derived from the audited funds.
5. Method
5.1 Define the question first. Before diligence starts, the LP records the role the commitment would play in its portfolio, the intended size range and its own constraints: eligibility, exclusion policies, liquidity needs, reporting needs. A fund that cannot meet a hard constraint is declined at screening and the reason is recorded.
5.2 Work in stages, with gates.
| Stage | Output | Gate |
|---|---|---|
| 1. Screening | Fit with the LP's mandate; decision to proceed | Proceed or decline, with reason |
| 2. Investment due diligence | Findings by domain (5.4) | No unresolved DISQUALIFYING finding |
| 3. Verification | Reconciliations and independent checks (5.5–5.7) | Material claims verified, or the gap recorded as a finding |
| 4. Operational due diligence | ODD report | ODD gate (5.9) |
| 5. Terms and legal review | Negotiated terms; counsel's review | Terms within the LP's policy, or exceptions approved |
| 6. Decision | IC memo with the findings log | Outcome under rule 6.4 |
| 7. Monitoring | Post-commitment record | Re-up assessment |
Stages 2 to 5 often run in parallel. The gates do not move.
5.3 Start from a standard questionnaire. The LP requests a standard DDQ and adds its own questions only where the standard form does not cover a point. ILPA describes its DDQ as a tool to reduce duplicated, customised questionnaires, not as a document every manager must adopt or one that meets every LP's needs. Its disclaimer states that no LP should use it as a substitute for its own judgement of what information it needs. Section 7 maps this framework's domains to the ILPA DDQ 2.0 and the AIMA questionnaire.
5.4 Investment due diligence domains.
| Domain | Core questions | Evidence that answers them |
|---|---|---|
| D1 Firm, ownership and succession | Who owns the firm and the GP entity? How are economics shared? Is there a succession plan? Who are the key persons? | Ownership chart; GP economics; succession plan; draft key person clause |
| D2 Strategy | What is the thesis and the opportunity set? Is the new fund the same strategy as its predecessors? Is the fund size consistent with the opportunity set? | Strategy description compared with the actual portfolios of predecessor funds |
| D3 Investment process | How are deals sourced, underwritten, approved and exited? Who sits on the investment committee and how does it vote? What portfolio construction limits apply? | Investment committee memos (inspected on site), process documents, portfolio data |
| D4 Team | Is the team capable of the strategy? What are tenure and turnover? Who holds decision rights? What outside activities compete for time? | Team templates, departures with reasons, references |
| D5 Alignment | How are compensation and carried interest allocated and vested? How large is the GP commitment and how is it funded: cash, management-fee waiver or borrowing? | DDQ answers, LPA, GP commitment documents |
| D6 Track record and performance | Can the reported returns be reproduced from cash flows? Who produced them? How do they compare with appropriate benchmarks? | Rules 5.5 and 5.6 |
| D7 Valuation and reporting | What is the valuation policy? Does it follow the IPEV Valuation Guidelines, and where does it deviate? Who reviews valuations? What does the reporting package contain? | Valuation policy, valuation committee records, mark history against realisations, sample reports |
| D8 Terms | Management fee and offsets, carried interest, hurdle rate, catch-up, clawback, waterfall, key person, LPAC, removal, investment period and fund term extensions | LPA and side letter review under the Fund Terms & Alignment Framework |
| D9 Fund financing and special transactions | How are subscription lines and NAV facilities used? How are co-investments allocated? Has the manager run continuation vehicles and how? | Facility terms, usage history, allocation policy, past transaction records |
| D10 Legal, regulatory and responsible investment | What is the manager's registration status? Is there litigation, enforcement or disciplinary history? Do sanctions screens clear? How are conflicts managed? What ESG policy and reporting apply, where the LP's policy requires them? | Regulatory records, court and enforcement records, sanctions lists, conflicts policy, ESG reports |
Two points in D8 are commonly misstated. "Investment period" and "commitment period" are often used as two names for the same period; if a document uses both, it must define the difference. A full catch-up and a partial catch-up are both used; neither is a defect by itself. What matters is the resulting split of profits and when the GP receives it.
5.5 Reconstruct performance; do not accept it.
- Recompute fund-level IRR and multiples from the cash flows and the latest NAV, and reconcile them to the audited financial statements. The ILPA DDQ asks for cash flows that allow net and gross IRRs and multiples to be calculated and that reconcile to the financial statements.
- Obtain both net and gross figures and explain the difference: management fees, fund expenses and carried interest. Under the US Marketing Rule (17 CFR 275.206(4)-1(d)(1)), an adviser registered or required to be registered with the SEC may not present gross performance in an advertisement unless it also presents net performance with at least equal prominence, in a format designed to facilitate comparison, calculated over the same time period and using the same type of return and methodology. A pitch book from such an adviser that shows only gross returns is a finding.
- Obtain returns with and without the effect of subscription lines. The ILPA DDQ asks for net and gross IRR both with and without use of credit facilities, and ILPA's 2020 guidance sets out disclosures that let LPs see the effect. A line can raise IRR while lowering the multiple (Example 1).
- Treat IRR as what it is: a money-weighted return. For closed-end funds in which the manager controls the timing of capital calls and distributions, GIPS 2020 permits money-weighted returns. A time-weighted return computed on quarterly NAVs is driven largely by unrealised marks. It is not a cleaner measure of skill.
- Read TVPI as DPI plus RVPI. Only the RVPI component depends on unrealised marks (Example 2).
- Benchmark in two ways. Compare with peer funds of the same strategy, region and vintage year, stating which vintage convention the peer data uses (first close, first capital call or first investment). Compare with public markets using a named public market equivalent and a named index: the Kaplan–Schoar PME is a ratio, the Long–Nickels PME produces an IRR to set against the fund's IRR, and Direct Alpha is an annualised excess return (Example 3). Where a manager claims GIPS compliance and presents a PME, GIPS requires the index to be disclosed.
- Analyse dispersion and concentration at deal level: the distribution of gross multiples, the share of value from the largest contributors, and losses under a stated loss ratio convention (Example 4).
- Separate realised from unrealised results, and compare past marks with eventual exit values (see the Valuation & Mark Quality Framework).
- Ask what is missing. The ILPA DDQ asks whether any predecessor-fund investments are excluded from the track-record appendices and why, and asks for examples of investments with a multiple below 1.0x and what was done about them. An unexplained exclusion is a finding.
- Do not read a quartile rank as proof of skill. Kaplan and Schoar (2005) found that returns persist across a manager's successive funds. Korteweg and Sorensen (2017) found long-term persistence, but also that performance is noisy enough that top-quartile realised returns do not reliably identify top-quartile skill. A quartile label is an input, not a conclusion.
5.6 Attribute the track record. For each material investment, record who sourced it, who led it, who sat on the board and who managed the exit, and whether those people are on the team for the new fund. Investments made at a prior firm are recorded separately, with the evidence that the individual led them and the basis on which the manager may present them. Attribution claims are checked against sources independent of the manager where they exist: the prior firm's or the portfolio company's own announcements, board records in company registers, and references.
5.7 Verify what matters independently. Each material claim needs at least one item of independent evidence, or the gap is recorded as a finding:
- performance: audited financial statements, and capital account statements of existing LPs where they consent to share them;
- registration status and disclosed history: the regulator's own records, for US advisers Form ADV through the SEC's public disclosure site; an exempt reporting adviser files reports on Form ADV but is not registered;
- litigation and enforcement: court and regulator records in the relevant jurisdictions;
- sanctions: the official lists that bind the LP, for US persons including OFAC's Specially Designated Nationals List;
- team history: prior employers' and portfolio companies' public records;
- conduct: back-channel references as well as manager-supplied ones. The LP's policy sets how many references of each type; the IC memo records how many were taken, of which types, and who chose them.
5.8 Keep a findings log. Each finding records its domain, a one-sentence statement, the evidence (document, version, page), whether that evidence is independent of the manager, its severity class, the owner, its status and the resolution with its date.
5.9 The ODD gate. An investment approval does not proceed while ODD has an unresolved DISQUALIFYING finding. ODD runs as a separate workstream, under the Operational Due Diligence Framework, and at minimum covers:
- the fund administrator: independence from the manager, scope of services and, where available, a controls report such as a SOC 1 report or an ISAE 3402 type 2 report, which covers the operating effectiveness of controls over a period;
- the auditor and the audit scope;
- custody and cash controls. Under the US custody rule (17 CFR 275.206(4)-2(b)(4)), an adviser registered or required to be registered with the SEC is deemed to meet the annual surprise-examination requirement for a pooled vehicle if the vehicle is audited at least annually, and on liquidation, by an independent public accountant registered with, and subject to regular inspection by, the PCAOB, and its audited GAAP financial statements are distributed to all investors within 120 days of the end of its fiscal year and promptly after the liquidation audit;
- valuation governance;
- the compliance programme and conflicts management;
- cybersecurity risk and business continuity;
- insurance;
- the manager's own KYC and AML procedures.
Self-administration, or valuation without independent review, is a risk factor to be assessed against the strategy, size and controls of the manager. It is not by itself an automatic rejection.
5.10 Decide on the record. The IC memo states the recommendation, every finding by severity, the conditions attached, any dissent, and what was not verified and why.
5.11 Monitor, and re-diligence before a re-up. After commitment the LP reviews quarterly reports and capital accounts, annual audited statements, and events: key person changes, regulatory events, litigation, GP-led transaction proposals, changes in strategy. A re-up is not automatic. It is a fresh decision focused on what has changed since the last diligence, and every carried-forward finding is re-dated.
6. Classification rules
6.1 Finding severity. This framework uses four classes. An LP may use its own scale, but it must define each class and its effect in the same way.
| Class | Meaning | Effect on the decision |
|---|---|---|
| DISQUALIFYING | A finding that, if unresolved, makes the commitment unacceptable | Decline unless resolved with evidence before approval |
| MATERIAL | A finding that affects the risk or terms of the commitment | Approval only with a recorded condition |
| MONITOR | A finding acceptable now that could become material | Tracked after commitment |
| NOTED | Recorded for completeness | None |
6.2 DISQUALIFYING by default. The following are DISQUALIFYING unless the LP's decision-maker overrides the classification with a recorded reason:
- Track-record figures that cannot be reconciled to audited financial statements or to cash flows, with no adequate written explanation.
- A material misstatement or omission in the manager's materials, found through independent evidence: for example litigation, an enforcement action or a disciplinary event that a court or regulator record shows and the manager did not disclose. Under US Rule 206(4)-8(a)(1), it is a fraudulent, deceptive or manipulative act for any investment adviser to a pooled investment vehicle to make an untrue statement of a material fact, or to omit a material fact needed to make its statements not misleading, to an investor or prospective investor in the vehicle.
- A confirmed match of the manager, a principal or the fund against a sanctions list that prohibits the LP from dealing with them.
- Refusal to provide information the LP's policy requires, without a lawful reason.
- An unresolved DISQUALIFYING finding from ODD.
6.3 MATERIAL by default. Examples: performance shown gross only; investments excluded from the track record without explanation; key person concentration with no succession plan; a GP commitment funded largely by fee waivers or borrowing; unexplained deviations from the IPEV Guidelines; no independent review of valuations in a strategy dominated by assets valued on unobservable inputs; terms outside the LP's policy; unexplained senior departures; a change of strategy between funds that the manager has not explained.
6.4 Decision outcomes.
| Outcome | Use |
|---|---|
| APPROVE | No unresolved DISQUALIFYING or MATERIAL finding. |
| APPROVE WITH CONDITIONS | MATERIAL findings are addressed by conditions: before closing (side letter terms, remediation evidence) or after (monitored commitments). |
| DECLINE | An unresolved DISQUALIFYING finding, or a judgement that the risks outweigh the case. |
| DEFER | Evidence is missing. The record states which evidence would change the decision. |
6.5 Proportionality has a floor. The depth of diligence may scale with the size of the commitment and the LP's exposure. These checks never drop out: performance reconstructed from cash flows; registration and disclosure check; sanctions screen; litigation search; legal review of the LPA and side letter; at least one reference the manager did not supply; and the ODD gate. Where an LP omits one, the IC memo says so.
6.6 No composite score. This framework does not combine findings into a numeric score. A score hides the one finding that should have stopped the commitment.
7. Mapping to ILPA DDQ 2.0 and the AIMA questionnaire
7.1 ILPA DDQ 2.0. The ILPA Due Diligence Questionnaire 2.0 (updated November 2021) covers 20 topics in short-form (yes/no) and long-form questions, with appendices for requested documents (A) and templates for team members (B), references (C), third parties and technology tools (D), fund performance and cash flows (E), portfolio investments (F), GP-led secondaries and continuation funds (G) and credit facilities (H). Its ESG section draws on the PRI's responsible investment DDQ for LPs.
| Framework domain | ILPA DDQ 2.0 section | Appendix |
|---|---|---|
| D1 Firm, ownership and succession | 1 Firm: General Information; 3 Succession Planning / Key Persons | B |
| D2 Strategy | 4 Investment Strategy; 11 Market Environment | – |
| D3 Investment process | 8 Investment Process | – |
| D4 Team | 9 Team | B |
| D5 Alignment | 10 Alignment of Interests | – |
| D6 Track record and performance | 14 Track Record | E, F |
| D7 Valuation and reporting | 15 Accounting / Valuation; 16 Reporting | – |
| D8 Terms | 2 Fund: General Information; 12 Fund Terms | – |
| D9 Fund financing and special transactions | 5 Co-Investments; 6 GP-Led Secondaries / Continuation Funds; 7 Credit Facilities | G, H |
| D10 Legal, regulatory and responsible investment | 13 Firm Governance / Risk / Compliance; 17 Legal; 19 ESG; 20 Diversity, Equity and Inclusion | – |
| ODD gate (5.9) | 13; 15; 18 Data Security / Technology / Third-Party(s) | A, D |
| References (5.7) | – | C |
Questions this framework relies on directly: 7.2 (use of subscription lines by predecessor funds over the past five years); 14.4 (investments excluded from the track-record appendices); 14.5 (examples of investments below 1.0x TVPI and what was done); 14.6 (private and public market benchmarks, with and without credit facilities); 15.7 (whether the fund follows the IPEV Guidelines, and deviations); 15.8 (independent valuation firm); 16.12 (GIPS compliance claim and GIPS Report); 17.2 (litigation and other legal proceedings); Appendix E1 (net and gross IRR with and without credit facilities; TVPI, DVPI and RVPI as the DDQ labels them, gross and net of fees) and E2 (cash flows that reconcile to the financial statements).
7.2 AIMA questionnaire. For hedge funds and for private credit managers, the AIMA Illustrative Questionnaire for the Due Diligence of Investment Managers is the usual base. The 2025 edition keeps the modular structure AIMA adopted in 2017, is the first to cover private credit and private equity managers as well as hedge funds, and issues its private-credit modules also under the ACC name. AIMA lists updated topics including performance presentation, outsourcing and technology risks, counterparty, leverage and liquidity risk management, anti-money laundering and expense disclosures. The full questionnaire is available to AIMA members, so this framework maps to it by topic rather than by question number: performance presentation to D6; leverage, liquidity and counterparty risk to D9 and the ODD gate; outsourcing and technology to the ODD gate; anti-money laundering to D10 and the ODD gate; expense disclosures to D8.
7.3 What the questionnaires do not do. A DDQ is a request instrument. It records what the manager says. It does not verify the answers, classify findings or reach a decision. Rules 5.5 to 6.6 supply those steps.
8. Family office variant
The evidence rules, domains, severity classes and gates above apply unchanged to a family office. This section covers what differs.
8.1 Classify the office first. Whether the investor is a single-family office, a multi-family office or another arrangement changes whose capital is at stake and who must be satisfied. A multi-family office allocating client families' capital is acting for others and carries duties to them. Classification follows the Family Office Classification Standard.
8.2 Record who decides. Family office decisions may rest with a principal, a CIO with delegated authority, or a committee that includes family members. The findings log and decision record are the same in each case. When a principal decides on conviction, the record still lists the findings, and what was not verified.
8.3 Capacity and reliance. A small office may have no in-house ODD capacity. It may commission ODD from a specialist, rely on an adviser, an OCIO or a consultant, or rely on a co-investor's diligence. A report the office relies on is recorded as an input with its author, date and scope. It is not independent verification of the manager unless its author verified the point. The minimum checks in rule 6.5 still apply, or the record says which were omitted.
8.4 Introductions are not evidence. An introduction from a trusted contact can start a process. It does not verify anything. The introducer and any economic interest it has in the outcome, such as a fee or a co-investment, are recorded as a potential conflict.
8.5 Eligibility of the subscribing vehicle. Subscription documents ask the investor to represent its status, and the status belongs to the vehicle that subscribes, not to the family. In the United States:
- a family office as defined in the SEC family office rule is an accredited investor under Rule 501(a)(12) if it has assets under management in excess of $5,000,000, was not formed for the specific purpose of acquiring the securities offered, and its prospective investment is directed by a person who has such knowledge and experience in financial and business matters that the family office is capable of evaluating the merits and risks of the prospective investment;
- a family client of such an office is an accredited investor under Rule 501(a)(13) when its investment is directed by that office;
- for a fund that admits only qualified purchasers, section 2(a)(51)(A)(ii) of the Investment Company Act covers a company that owns not less than $5,000,000 in investments and is owned directly or indirectly by or for two or more natural persons related as siblings or spouses (including former spouses) or as direct lineal descendants by birth or adoption, their spouses, their estates, or foundations, charitable organisations or trusts established by or for them, with "investments" defined in Rule 2a51-1.
The office and its counsel decide which vehicle subscribes and which test it meets. The manager decides whether to accept the subscription. A diligence file records the representation made, not a conclusion about status.
8.6 Reporting the family can use. Families often consolidate many entities and taxable vehicles. Diligence checks that the manager's reporting package, including the ILPA Reporting Template where the manager uses it, gives the office what it needs to consolidate positions and meet the family's tax reporting timetable.
8.7 Co-investment expectations. Where co-investment access is part of the reason to commit, diligence covers the manager's allocation policy (ILPA DDQ section 5) and the office's own ability to decide within co-investment timetables. A side letter that states an interest in co-investment does not commit the manager to allocate any unless it is drafted to do so.
8.8 Values and exclusions. If the family has exclusion policies, diligence checks how they can be implemented: excuse rights in the LPA, side letter provisions or a separate account. A manager's own responsible investment policy does not bind it to the family's exclusions.
8.9 Reliance on one person. An office may commit because of trust in one individual at the manager. That makes the key person clause and succession planning more important to the office, not less.
9. Conflict handling
9.1 The same figure differs between documents. Before treating it as a discrepancy, check that both figures use the same definition (net or gross; with or without subscription lines; LP share or total including the GP's commitment; regulatory assets under management or a marketing figure), the same as-of date and the same scope (one fund, or the fund with its parallel vehicles). Most differences resolve here into two correctly labelled figures.
9.2 A real discrepancy. Where the difference survives those checks, the source that covers the figure governs for what it covers: audited financial statements for the amounts they report at their date; a regulatory filing for what the form requires, as the form defines it; a reconstruction from cash flows over a summary figure. The manager is asked for a written reconciliation. If none is adequate, the discrepancy is a finding, classified under rule 6.2 or 6.3.
9.3 References disagree. Each reference is recorded with its source and how it was obtained. A negative reference with specific, checkable content is followed up in writing and, where possible, with another independent reference. References are not averaged into a sentiment score.
9.4 The manager disputes a finding. The manager's response and evidence are recorded beside the finding. The finding is reclassified only on evidence, and the history keeps both versions.
9.5 The diligence team disagrees. Dissent is recorded in the IC memo with its reasons.
10. Confidence and limitations
- Diligence reduces the risk of a bad commitment. It does not remove it. A misrepresentation designed to survive diligence can pass a well-run process.
- Persistence of manager performance is uncertain at the level of a single manager. Research cited in rule 5.5 finds persistence on average and large noise in individual results.
- Emerging managers' track records often rest on investments made at prior firms, where attribution evidence is incomplete.
- References are selected, by the manager or through the LP's own network. Neither set is a random sample.
- Regulatory filings are filers' statements. A manager's absence from one regulator's records says nothing about its standing with another.
- A standard DDQ does not claim completeness. ILPA's disclaimer states that no representation is made that its DDQ will include all information an LP needs.
- Unrealised value depends on marks, and peer benchmarks depend on which funds report to the data provider and on its vintage convention.
- The framework deliberately publishes no market norms for fees, carried interest, hurdles, GP commitment or timelines. Such norms vary by strategy, fund size and date, and are covered with dated sources in the Fund Terms & Alignment Framework.
11. Temporal rules
- Every input carries a version and an as-of date. Performance is stated as of a named quarter end.
- If a quarter has closed since the performance data was received, the data is updated before approval or the IC memo states the as-of date it relied on.
- Registration status, sanctions screening and litigation searches are rerun close to signing and again at each re-up. The LP's policy sets the maximum age; the record shows the date of each check.
- A finding carries the date it was raised and the date it was resolved. Resolved findings remain in the history.
- Regulatory references are dated, and recent changes are flagged:
- The SEC's 2023 private fund adviser rules (including the quarterly statement, audit and adviser-led secondaries rules) were vacated by the US Court of Appeals for the Fifth Circuit on 5 June 2024 (National Association of Private Fund Managers v. SEC). They are not requirements and are not used as a diligence standard.
- FinCEN's AML/CFT programme rule for investment advisers had its effective date postponed from 1 January 2026 to 1 January 2028.
- The 2025 edition of the IPEV Valuation Guidelines is in effect for quarterly reporting periods beginning on or after 1 April 2026, with early adoption encouraged. It supersedes the December 2022 edition, which applied to reporting periods beginning on or after 1 January 2023.
- ILPA's Reporting Template v2.0 and Performance Template were released in January 2025. The reporting template applies from the Q1 2026 report to funds then in their investment period or commencing operations on or after 1 January 2026; the performance template applies to funds commencing operations on or after 1 January 2026.
- ILPA's 2023 continuation fund guidance is under revision: a draft was released on 24 June 2026, with comments closed on 5 August 2026.
- Monitoring runs on reporting events (quarterly reports, annual audited statements) and on events (key person changes, regulatory or legal events, GP-led proposals). It is not a guarantee that every event is detected when it happens.
12. Edge cases
- First-time funds and spin-outs. There is no fund-level track record. Diligence rests on deal-level attribution from prior firms, on whether the manager may present those results, and on the team's operational readiness. See the Emerging Manager Evaluation Framework.
- Re-ups. The previous diligence file is an input, not a substitute. Every carried-forward finding is re-dated and re-checked.
- Continuation vehicles. ILPA's 2023 guidance addresses the absence of a true status quo option, short decision timelines and incomplete disclosure, and asks GPs to engage the LPAC on conflicts. ILPA DDQ section 6 and Appendix G collect the manager's history. Full evaluation follows the Secondaries & Continuation Vehicle Evaluation Framework.
- Co-investments. A co-investment alongside a fund needs its own deal diligence; the fund diligence covers the allocation process, not the deal.
- Open-ended, evergreen and hedge funds. Liquidity terms (notice periods, gates, suspension rights) and valuation frequency become central. GIPS requires time-weighted returns unless the money-weighted conditions are met, so time-weighted returns are the norm for these vehicles. The AIMA questionnaire is the usual base.
- Managers that are not SEC-registered. An exempt reporting adviser files reports on Form ADV (17 CFR 275.204-4(a)) but is not registered. A manager regulated outside the United States is checked on its home regulator's register. Absence from US records is not negative evidence about such a manager.
- Fund of one or separately managed account. Terms are negotiated, but administrator, custody and valuation checks still apply.
- Claims of GIPS compliance. The LP requests the GIPS Report for the fund (ILPA DDQ 16.12) and checks that the performance provided in diligence was prepared on the same basis.
- Placement agents. The agent's role and fee are recorded. Its materials are manager-supplied.
13. Worked examples
All examples are illustrative. Each figure can be reproduced from the data given.
Example 1: a subscription line raises IRR and lowers the multiple. A fund calls 100 from LPs on 1 January 2020 and distributes 80 on 1 January 2023 and 80 on 1 January 2025. Net IRR is 12.7% and TVPI is 1.60x. Now the same investment is financed on 1 January 2020 by a subscription line, repaid by an LP capital call of 102 (100 plus 2 of interest and fees) on 1 January 2021. Distributions are unchanged. IRR rises to 16.6%; TVPI falls to 1.57x (160 / 102). The underlying investment is the same. Diligence compares IRRs only on the same basis, which is why the ILPA DDQ asks for both.
Example 2: how much of TVPI is marks. Paid-in capital is 80, cumulative distributions 20 and NAV 100. DPI is 0.25x, RVPI 1.25x and TVPI 1.50x. Of the total value of 120, 100 (83%) is unrealised and depends on the valuation policy.
Example 3: three public market equivalents, three meanings. An LP contributes 100 at year 0; the fund distributes 30 at year 2 and 60 at year 3, with a NAV of 70 at year 3. A public index stands at 100, 110, 121 and 133.1 at years 0 to 3 (10% a year).
| Measure | Result | Reading |
|---|---|---|
| Fund IRR | 18.3% | money-weighted return of the fund |
| KS-PME | 1.22 | the fund's distributions and NAV are worth 22% more than the same contributions invested in the index |
| Long–Nickels PME IRR | 10.0% | the IRR of the index-replicating portfolio, to set against the fund's 18.3% |
| Direct Alpha | 7.5% a year | annualised excess return over the index |
None of these is "the" PME. A diligence memo names the variant and the index it used.
Example 4: three loss ratios from one portfolio. Ten investments total 100 of invested capital. Three are valued below cost: 10 now worth 4, 5 worth 2, and 5 worth 0.
| Convention | Result |
|---|---|
| Share of investments below cost (count) | 3 of 10 = 30% |
| Share of invested capital in investments below cost | 20 of 100 = 20% |
| Capital lost as a share of invested capital | 14 of 100 = 14% |
The other seven investments (80 of cost) are valued at 168, so the portfolio's gross multiple is (168 + 6) / 100 = 1.74x. A loss ratio is meaningful only with its convention stated.
Example 5: a discrepancy that is a definition. A DDQ states a net TVPI for Fund II that is higher than the figure the LP reconstructs from the audited statements and cash flows at the same date. The pre-checks in rule 9.1 show that the DDQ figure includes the GP's own commitment, which pays no fees or carry. The LP-only figure is used. The finding is recorded as NOTED, with a request that future materials label the basis. Had the manager been unable to explain the difference, the finding would be DISQUALIFYING by default under rule 6.2.
Example 6: a family office's subscribing vehicle. A single-family office with assets under management well above $5,000,000 directs an investment by a family holding partnership into a fund offered only to accredited investors. The office's CIO directs the investment. The diligence file records the representation the holding partnership makes in the subscription agreement (for example, family client of a qualifying family office under Rule 501(a)(13), or an entity test), the counsel who confirmed it, and the date. It does not record a conclusion that the family "is accredited": the status belongs to the vehicle that subscribes, and the manager decides whether to accept it.
14. External references
- ILPA Due Diligence Questionnaire 2.0 (November 2021). The base questionnaire this framework maps to (section 7). This framework adds what a questionnaire does not: verification rules, finding classes, decision outcomes and gates.
- AIMA Illustrative Questionnaire for the Due Diligence of Investment Managers (2025 edition). Mapped by topic (7.2).
- ILPA Principles 3.0 (2019), ILPA Model LPA, ILPA guidance on subscription lines (2020) and continuation funds (2023), ILPA Reporting Template v2.0 and Performance Template (2025). Terms, financing, GP-led transactions and reporting; see also the ILPA Principles.
- GIPS Standards for Firms 2020. Conditions for money-weighted returns and PME index disclosure; see GIPS.
- SEC Marketing Rule (17 CFR 275.206(4)-1). Net performance alongside gross; see marketing rule.
- IPEV Valuation Guidelines (2025 edition), ASC 820 and IFRS 13. Fair value as an exit price at the measurement date.
- Form ADV and the Investment Adviser Public Disclosure site; Rule 204-4. Registration and reporting status of US advisers.
- OFAC Specially Designated Nationals List. Sanctions screening for US persons.
- SEC custody rule (17 CFR 275.206(4)-2) and Rule 206(4)-8; SOC 1 and ISAE 3402. ODD gate items and the anti-fraud basis for rule 6.2.
- Academic research. Kaplan and Schoar (2005) and Korteweg and Sorensen (2017) on persistence; Long and Nickels (1996), Kaplan and Schoar (2005) and Gredil, Griffiths and Stucke (2023) on public market equivalents and Direct Alpha.
- Where this framework differs from common practice. It publishes no market norms for fees, carry, hurdles, GP commitment or diligence timelines without a dated source. It does not score managers. It treats a regulatory filing as the filer's statement, not a verification.
15. Version and change log
- Version 1.0.0 (2026-10-01). Rewrite of the LP due diligence checklist, keeping its address, and absorbing the family office due diligence process page as section 8. Removed: every unsourced statistic (including a loss-rate multiple attributed to "industry data", diligence timelines, reference-call counts, fee and GP-commitment norms, family-office survey percentages and secondary-market volumes), a product section, and the repeated master checklist. Corrected: IRR versus time-weighted returns, PME variants, loss ratio conventions, vintage year assignment, catch-up, investment versus commitment period, TVPI and marks, and the claim that funds without independent administrators are always rejected. Added: evidence and verification rules, finding classes, decision outcomes, the ODD gate, the ILPA DDQ 2.0 and AIMA mappings, eligibility representations for family vehicles, and dated regulatory status notes.
- Version 1.1.0 (2026-10-01). Independent review. Example 4 now states the value of the seven investments not below cost, so the 1.74x gross multiple can be reproduced; the ILPA Reporting Template scope in 11(5) states the investment-period condition; worked-example preamble no longer refers to an internal formula library.
- Version 1.2.0 (2026-10-02). Specialist review of the US legal and regulatory statements against their primary sources. Corrected: the Marketing Rule scope and conditions (5.5(2)); the Rule 206(4)-8 wording (6.2(2)); the family office accredited investor test (8.5); the IPEV edition dates (11(5)). Narrowed: the custody rule audit provision (5.9), the qualified purchaser family company test (8.5), the Fifth Circuit vacatur (11(5)) and exempt reporting adviser filings (12).
Change control. Changes to the finding classes, the default DISQUALIFYING list, the minimum checks in rule 6.5 or the ODD gate are major changes. New mappings, examples and clarifications are minor changes.
Concepts used
- Due Diligence
- Investment Due Diligence
- Operational Due Diligence (ODD)
- Due Diligence Questionnaire (DDQ)
- Data Room
- Track Record
- Track Record Attribution
- Key Person Clause
- Limited Partnership Agreement (LPA)
- Side Letter
- Subscription Line of Credit
- Kaplan–Schoar Public Market Equivalent (KS-PME)
- Direct Alpha
- Loss Ratio
- Emerging Manager
- Family Office
Sources
- ILPA Due Diligence Questionnaire 2.0 (and Diversity Metrics Template). Institutional Limited Partners Association, ILPA, Version 2.0, November 2021 (v1.1 dated October 2013). Status: Current (checked 2026-10-01). Overview (topics 1-20; 'not intended to be a required document'); disclaimer; Table of Contents (Appendices A-H); questions 7.2, 14.4, 14.5, 14.6, 15.7, 15.8, 16.12, 17.2; Appendix E1 and E2
- AIMA Illustrative Questionnaire for the Due Diligence of Investment Managers (2025 edition). Alternative Investment Management Association, AIMA, 2025 edition (modular). Status: Current; full questionnaire available to AIMA members only (checked 2026-10-01). 'Presenting the 2025 edition' article
- 17 CFR 275.206(4)-1 - Investment adviser marketing (Marketing Rule). U.S. Securities and Exchange Commission (CFR text via eCFR; LII mirror), eCFR current as of 2026-09-29; last amended 2022-04-15 (later versions technical). Status: in force (checked 2026-10-01). 275.206(4)-1(a) introductory text; (d)(1)(i)-(ii)
- Global Investment Performance Standards (GIPS) for Firms 2020. CFA Institute, 2020 edition; effective 1 January 2020; required for GIPS Reports with periods ending on or after 31 December 2020. Status: Current (checked 2026-10-01). Provisions 1.A.35 and 5.C.33
- GIPS Standards for Firms 2020 - Glossary (defined terms). CFA Institute, Glossary section of the 2020 edition. Status: Current (checked 2026-10-01). Public market equivalent
- Enhancing Transparency Around Subscription Lines of Credit. Institutional Limited Partners Association, ILPA, June 2020 (follows the June 2017 guidance Subscription Lines of Credit and Alignment of Interests). Status: Current (checked 2026-10-01). Recommended quarterly and annual disclosures
- Private Equity Performance: Returns, Persistence, and Capital Flows. Steven N. Kaplan; Antoinette Schoar, The Journal of Finance, Vol. 60(4), pp. 1791-1823, August 2005. Status: Published (journal paywalled; NBER w9807 working paper) (checked 2026-10-01). Persistence results; PME definition
- Skill and Luck in Private Equity Performance. Arthur Korteweg; Morten Sorensen, Journal of Financial Economics, Vol. 124(3), pp. 535-562. Status: Published (paywalled) (checked 2026-10-01). Main results
- A Private Investment Benchmark. Austin M. Long III; Craig J. Nickels, AIMR Conference on Venture Capital Investing (University of Texas System), Dated 13 February 1996. Status: Conference paper (not peer-reviewed) (checked 2026-10-01). Index Comparison Method
- Benchmarking Private Equity: The Direct Alpha Method. Oleg R. Gredil; Barry Griffiths; Ruediger Stucke, Journal of Corporate Finance, Vol. 81, 102360, August 2023; SSRN working paper 2014 (doi:10.2139/ssrn.2403521). Status: Published (paywalled) (checked 2026-10-01). Direct Alpha definition
- International Private Equity and Venture Capital Valuation Guidelines (2025 edition). IPEV Board, IPEV, Published 11 December 2025; in effect for quarterly reporting periods beginning on or after 1 April 2026; early adoption encouraged. Status: Current; supersedes the December 2022 edition (checked 2026-10-01). Preface ('in effect for quarterly reporting periods beginning on or after 1 April 2026. Early adoption is encouraged.'); Appendix 2 definition of Fair Value
- ASU 2011-04, Fair Value Measurement (Topic 820): Amendments to Achieve Common Fair Value Measurement and Disclosure Requirements in U.S. GAAP and IFRSs. Financial Accounting Standards Board, May 2011. Status: in force (codified in ASC 820) (checked 2026-10-01). ASC 820-10-35-2
- IFRS 13 Fair Value Measurement. IFRS Foundation / International Accounting Standards Board (IASB), Issued May 2011 by the IASB; later consequential amendments (IAS 19 2011, Annual Improvements 2011-2013, IFRS 9 2014, IFRS 16 2016, IFRS 18 2024, IFRS 19 2024). Status: in force (checked 2026-10-01). Definition of fair value
- ILPA Principles 3.0: Fostering Transparency, Governance and Alignment of Interests for General and Limited Partners. Institutional Limited Partners Association, ILPA, Third edition, released 27 June 2019. Status: Current edition (no 4.0 found as of 2026-10-01) (checked 2026-10-01). ILPA Principles 3.0 (2019), whole document
- ILPA Model Limited Partnership Agreement (Whole of Fund and Deal-by-Deal versions). Institutional Limited Partners Association, ILPA, Whole of Fund first released October 2019, updated July 2020; Deal-by-Deal version and term sheet released 22 July 2020. Status: Current (checked 2026-10-01). Whole of Fund and Deal-by-Deal model LPAs (2020)
- ILPA Reporting Template (v. 2.0). Institutional Limited Partners Association, ILPA, v2.0 released 21 January 2025 under the Quarterly Reporting Standards Initiative (QRSI). Status: Current; ILPA recommends implementation from Q1 2026 (checked 2026-10-01). Suggested Guidance, p. 9 and applicability table
- ILPA Performance Template (Granular Methodology and Gross Up Methodology), v1.1. Institutional Limited Partners Association, ILPA, Released January 2025 (QRSI); v1.1 April 2025. Status: Current; for funds commencing operations on or after 1 January 2026 (checked 2026-10-01). Scope and effective date
- Continuation Funds: Considerations for Limited Partners and General Partners. Institutional Limited Partners Association, ILPA, May 2023. Status: Current but under revision: draft Continuation Vehicle guidance released 24 June 2026, comments closed 5 August 2026; final not yet confirmed (checked 2026-10-01). Guidance themes; status note
- Form ADV (Uniform Application for Investment Adviser Registration and Report by Exempt Reporting Advisers) - SEC form cover and index. U.S. Securities and Exchange Commission, OMB No. 3235-0049; expires 2027-07-31. Status: in force (checked 2026-10-01). Index page, 'SEC's Collection of Information'
- Investment Adviser Public Disclosure (IAPD). U.S. Securities and Exchange Commission, Live database (accessed 2026-10-01). Status: current (checked 2026-10-01). Firm and individual search pages
- 17 CFR 275.204-4 - Reporting by exempt reporting advisers. U.S. Securities and Exchange Commission (CFR text via eCFR; LII mirror), eCFR current as of 2026-09-29; no substantive amendment since eCFR baseline. Status: in force (checked 2026-10-01). 275.204-4(a)
- Specially Designated Nationals and Blocked Persons List (SDN) - OFAC Sanctions List Service. U.S. Department of the Treasury, Office of Foreign Assets Control, Live list (accessed 2026-10-01). Status: current (checked 2026-10-01). SDN List page (accessed 2026-10-01)
- 17 CFR 275.206(4)-8 - Pooled investment vehicles. U.S. Securities and Exchange Commission (CFR text; LII mirror), Current CFR text as published by LII (accessed 2026-10-01); source 72 FR 44761, Aug. 9, 2007. Status: in force (checked 2026-10-01). 275.206(4)-8(a)(1), (b)
- 17 CFR 275.206(4)-2 - Custody of funds or securities of clients by investment advisers (Custody Rule). U.S. Securities and Exchange Commission (CFR text via LII mirror), Current text as served by LII on 2026-10-01; source line 75 FR 1484, Jan. 11, 2010. Status: in force (checked 2026-10-01). 275.206(4)-2(a) introductory text, (a)(4), (b)(4)(i)-(iii)
- SOC 1 - SOC for Service Organizations: ICFR. AICPA & CIMA, Web page accessed 2026-10-01. Status: Current (checked 2026-10-01). SOC 1 overview page
- International Standard on Assurance Engagements (ISAE) 3402, Assurance Reports on Controls at a Service Organization. International Auditing and Assurance Standards Board (IAASB), via IFAC, Issued December 2009; extract from the 2013 IAASB Handbook; effective for service auditors' reports covering periods ending on or after 15 June 2011 (para 7). Status: Current (checked 2026-10-01). Para 9(k)
- Announcement Regarding the Private Fund Advisers Rules. U.S. Securities and Exchange Commission, 2024-10-31. Status: current (checked 2026-10-01). List of vacated rules
- National Association of Private Fund Managers v. SEC, No. 23-60471 (5th Cir. June 5, 2024). U.S. Court of Appeals for the Fifth Circuit (via govinfo, USCOURTS collection), Decided 2024-06-05. Status: final (checked 2026-10-01). Decided 2024-06-05
- Delaying the Effective Date of the AML/CFT Program and SAR Filing Requirements for Registered Investment Advisers and Exempt Reporting Advisers (final rule), 91 FR 36. Financial Crimes Enforcement Network (Federal Register via govinfo), Effective as of 2025-12-31; published 2026-01-02. Status: in force (checked 2026-10-01). DATES section
- 17 CFR 230.501 - Definitions and terms used in Regulation D (accredited investor). U.S. Securities and Exchange Commission (CFR text via eCFR; LII mirror), eCFR current as of 2026-09-29; last amended 2025-02-18 (technical, 90 FR 9684); last substantive amendment effective 2020-12-08 (85 FR 64234). Status: in force (checked 2026-10-01). 230.501(a) introductory text, (a)(12)(i)-(iii), (a)(13)
- 15 U.S.C. 80a-2 - Definitions (Investment Company Act sec. 2, incl. 2(a)(48) BDC and 2(a)(51) qualified purchaser). U.S. Congress (United States Code; LII mirror), Current US Code text as published by LII (accessed 2026-10-01). Status: in force (checked 2026-10-01). Sec. 2(a)(51)(A)(ii)
- 17 CFR 270.2a51-1 - Definition of investments for purposes of section 2(a)(51) (qualified purchaser); certain calculations. U.S. Securities and Exchange Commission (CFR text via eCFR; LII mirror), eCFR current as of 2026-09-29; no substantive amendment since eCFR baseline (2016-12-31). Status: in force (checked 2026-10-01). 270.2a51-1(b)
- OFAC FAQ 18: What is an SDN?. Office of Foreign Assets Control, U.S. Department of the Treasury, Accessed 2026-10-02. Status: current (checked 2026-10-02). FAQ 18 'What is an SDN?'
- International Private Equity and Venture Capital Valuation Guidelines (December 2022 edition). IPEV Board, IPEV, Published 14 December 2022; effective for periods beginning on or after 1 January 2023. Status: Superseded by the 2025 edition for periods beginning on or after 1 April 2026 (checked 2026-10-01). Preface ('in effect for reporting periods beginning on or after 1 January 2023')
Related frameworks
Framework · Version 1.1.0
Fund Terms & Alignment Framework
A method for reviewing private fund terms: management fee base and step-downs, carried interest, preferred return, catch-up, whole-fund and deal-by-deal waterfalls, clawback, fee offsets, GP commitment and LP governance rights, with worked calculations and a mapping to ILPA Principles 3.0 and the Model LPA.
Standard · Version 1.2.0
Altss Private Markets Performance Measurement Standard
The Altss standard for calculating, labelling and comparing private-fund performance: money-weighted IRR on actual dates, NAV as terminal value, TVPI, DPI, RVPI and MOIC, gross versus net, subscription-line effects, pooled versus average figures, horizon returns, and GIPS 2020 and ILPA alignment.
Framework · Version 1.2.0
Private Capital Valuation & Mark Quality Framework
How unquoted private-capital investments and fund interests are marked to fair value under ASC 820, IFRS 13, the IPEV Guidelines (2025 edition) and Rule 2a-5, and the Altss-defined indicators used to read a mark: timeliness, staleness, divergence, dispersion and backtesting.

Standard · Version 1.2.0
Altss Family Office Classification Standard
How Altss classifies family offices: the SEC family office rule as a US regulatory exclusion rather than a general definition, accredited-investor family office categories, Altss-defined labels for single-, multi-, embedded and virtual family offices, adjacent types excluded, and the evidence each label requires.
Standard · Version 1.2
Altss Evidence & Provenance Standard
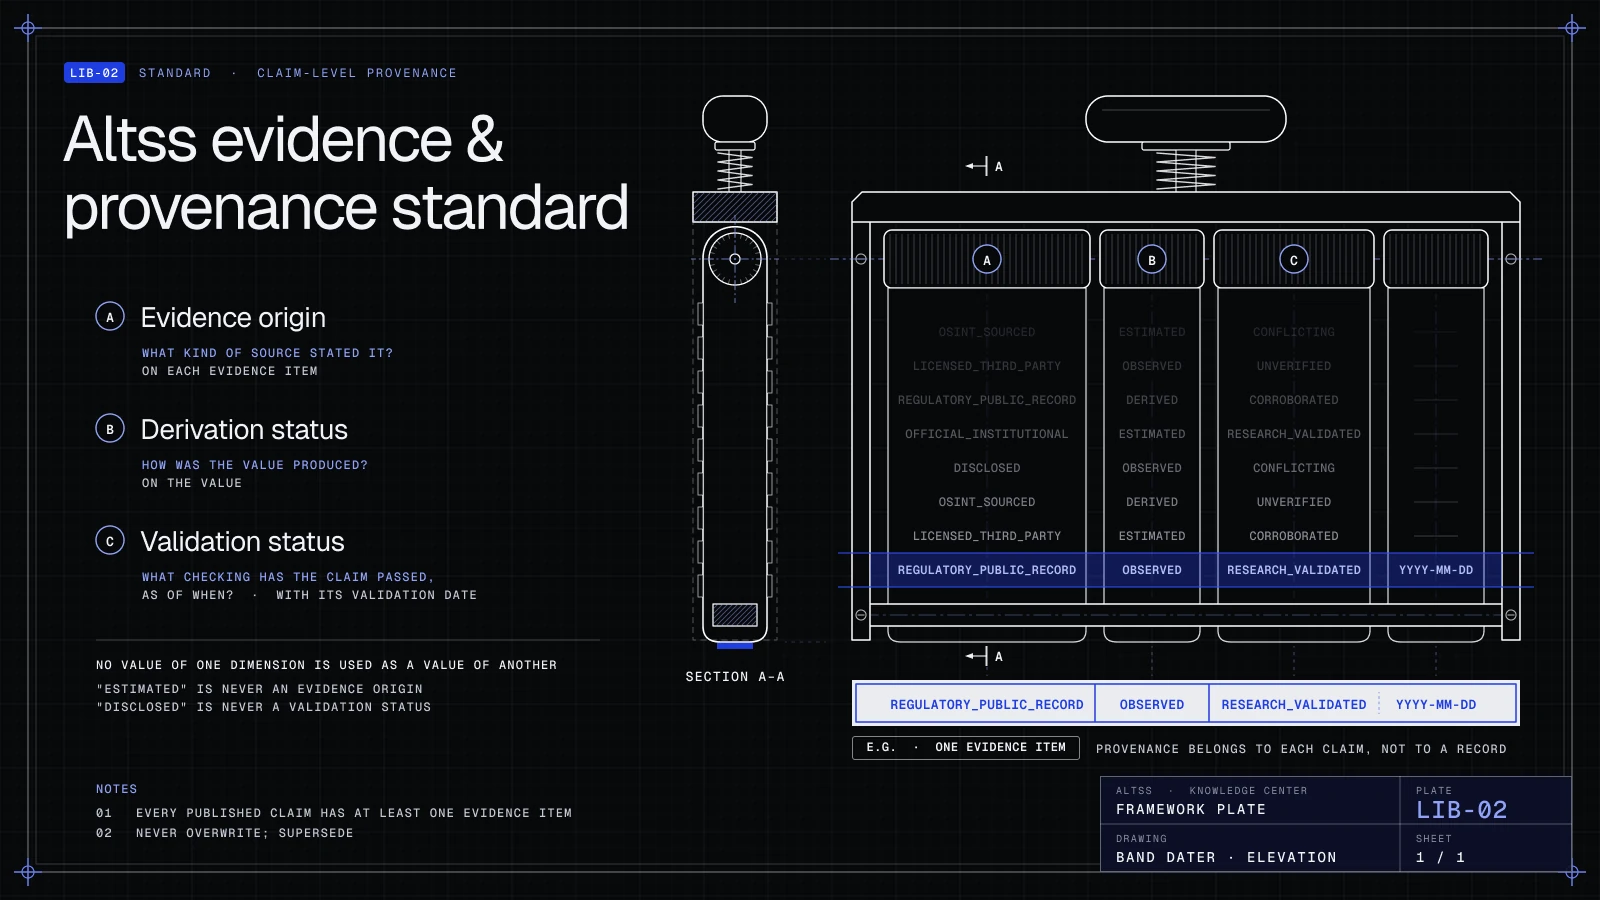
The Altss standard for recording evidence behind private-markets facts: claim-level provenance, evidence chains, three separate evidence dimensions (evidence origin, derivation status, validation status), distinct date types, null states such as unknown vs not disclosed, negative evidence, conflicts and claim citation.