Standard · Version 1.2.0 · Last reviewed
Source check: Legal and regulatory statements checked against the cited primary sources on (how). General information, not advice.
Altss Private Markets Performance Measurement Standard
The Altss standard for calculating, labelling and comparing private-fund performance: money-weighted IRR on actual dates, NAV as terminal value, TVPI, DPI, RVPI and MOIC, gross versus net, subscription-line effects, pooled versus average figures, horizon returns, and GIPS 2020 and ILPA alignment.
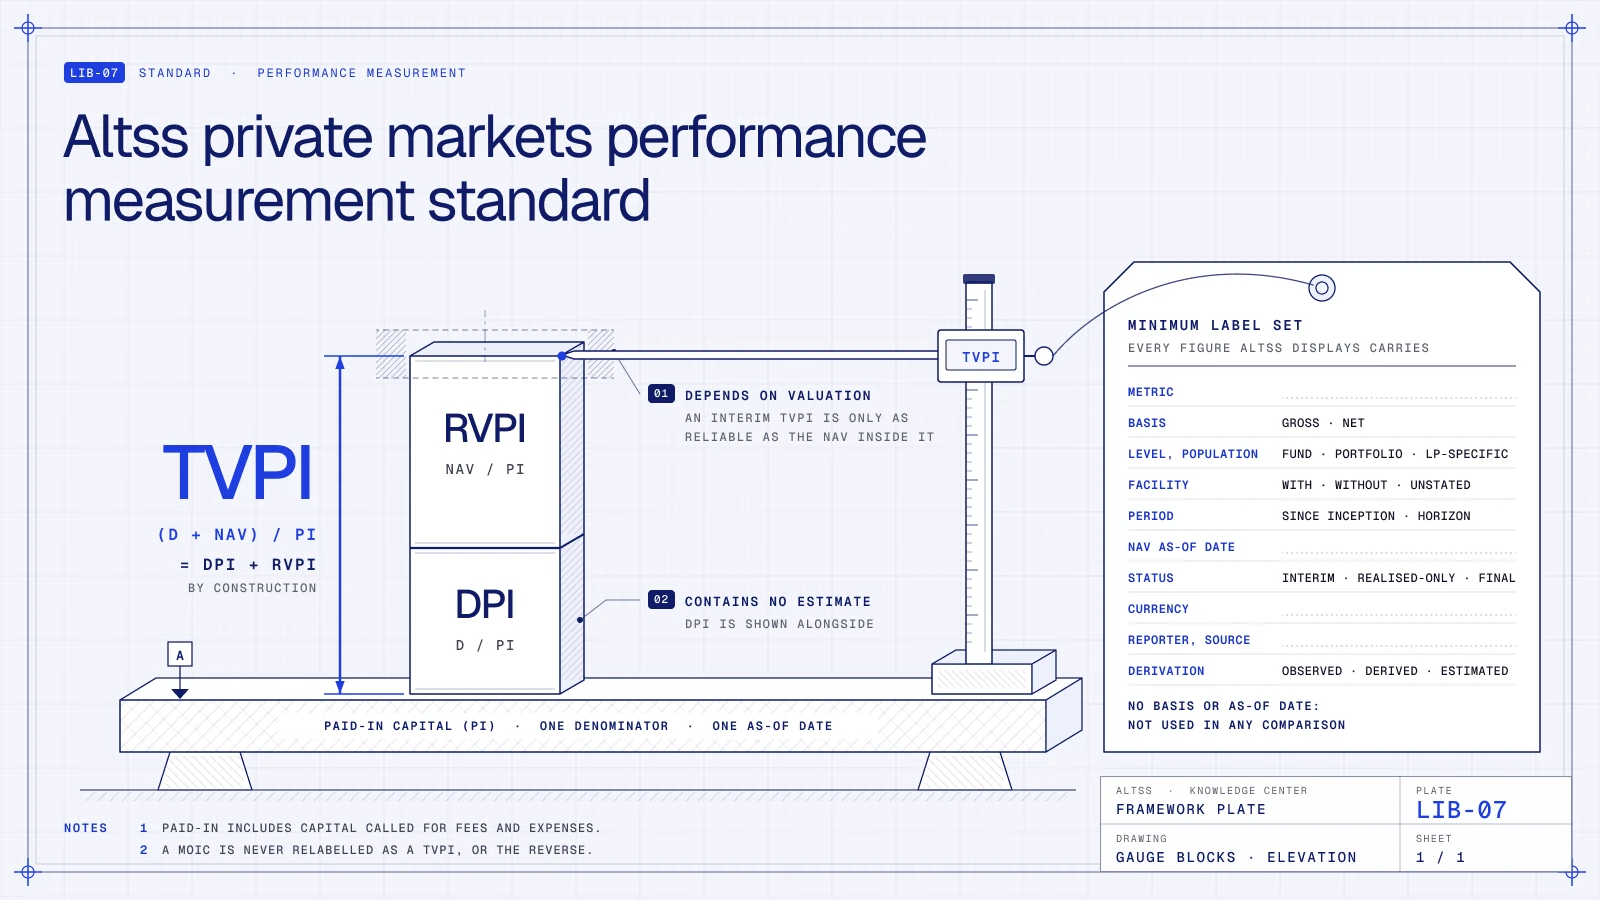
Reference plate: one paid-in denominator, one as-of date, and the labels a performance figure needs.
1. Purpose
This standard sets the conventions Altss applies when a performance figure for a private fund, or for an investment held by one, is calculated, labelled or compared in Altss reference content and records. It covers the money-weighted return (IRR, computed date-exact as XIRR), the paid-in multiples (TVPI, DPI, RVPI), MOIC, and the qualifiers without which none of these can be compared.
A private-fund performance number does not describe itself. Two correct IRRs for the same fund at the same date can differ by several percentage points because one is gross and the other net, one includes the effect of a subscription facility and the other removes it, or one is an individual LP's return on its own commitment and the other is the return of all fee-paying LPs together. The rules below require every figure to carry those qualifiers, so that a reader can reproduce it or see why it differs from another figure.
This publication replaces the earlier page at this address, "GP-LP Data Transparency Standards". That page described IRR as time-weighted (it is money-weighted), presented one vintage-year convention as universal, credited ILPA guidance to Altss analysis, and presented the US rule on showing gross with net performance as an investor preference. Section 13 lists the corrections.
2. Scope
In scope
- Closed-end, fixed-life private funds and their LP interests: buyout, growth, venture, private credit, real estate, infrastructure, funds of funds and secondaries funds.
- Fund-level figures (cash flows between the fund and its investors), portfolio-level figures (cash flows between the fund and its investments) and LP-specific figures.
- Since-inception and horizon returns; interim figures that include a NAV and final figures that do not.
- Aggregation of several funds or investments into one figure.
- Alignment with the GIPS 2020 Standards for Firms, the ILPA Performance Template and Reporting Template, and the gross/net requirements of the US SEC Marketing Rule.
Out of scope
- How the NAV inside an interim figure is estimated: see the Private Capital Valuation & Mark Quality Framework.
- Peer groups, quartiles, vintage cohorts and the choice and interpretation of public market equivalent (PME) methods: see the Private Markets Benchmarking Methodology. This standard fixes only the inputs and labels those comparisons need.
- Attribution of a track record to a team or firm: see the Track Record Attribution & Quality Framework.
- The fee and carried-interest terms that create the gap between gross and net: see the Fund Terms & Alignment Framework.
- Open-end and evergreen vehicles, for which time-weighted returns are the convention (touched only in section 10).
- Risk-adjusted ratios, after-tax returns and investment advice.
3. Definitions
- Internal rate of return (IRR). The discount rate at which the net present value of a series of dated cash flows equals zero. IRR is a money-weighted return: the GIPS 2020 glossary defines a money-weighted return as the return for a period that reflects the change in value and the timing and size of external cash flows.
- XIRR. IRR computed on actual cash-flow dates, with time measured in days from the first cash flow divided by 365.
- Time-weighted return (TWR). A return that links sub-period returns and, in the GIPS 2020 wording, negates the effects of external cash flows. It answers a different question from IRR; see time-weighted return vs IRR.
- Net IRR and gross IRR. Net is measured after the management fees, fund expenses and carried interest borne by the investors in the stated population; gross is measured before them. See gross vs net returns.
- Paid-in capital (PI). Cumulative contributions by LPs, including amounts called to pay fees and expenses.
- Distributions (D). Cumulative cash and in-kind distributions to LPs.
- Net asset value (NAV). The LPs' residual value in the fund at a stated as-of date, after accrued carried interest.
- TVPI, DPI, RVPI. (D + NAV) / PI, D / PI and NAV / PI. TVPI = DPI + RVPI by construction.
- PIC. Paid-in capital divided by committed capital.
- MOIC. Realised proceeds plus unrealised value, divided by the capital invested, measured at investment or portfolio level. See TVPI vs MOIC.
- Fund level, portfolio level, LP-specific. Fund-level figures use the cash flows between the fund and its investors; portfolio-level figures use the cash flows between the fund and its investments (this split follows the ILPA Performance Template). An LP-specific figure uses one investor's own capital account.
- Interim and final. An interim figure includes a NAV as a terminal value. A final figure is computed after the last distribution, with no remaining NAV.
- Since inception; horizon IRR. Since inception runs from the first cash flow to the measurement date. A horizon IRR runs between two stated dates and treats the NAV at the start as a contribution.
- Pooled IRR. The IRR of the combined, date-aligned cash flows and ending NAVs of several funds or investments.
- With and without a facility. A figure "with" a subscription line of credit uses the investors' actual contribution dates. A figure "without" it treats capital as called on the dates the facility was drawn.
- Vintage year. The year used to group funds for comparison; the convention must be stated (rule 5.12).
- Fee-paying LPs. The investor population used by the ILPA Performance Template for fund-level figures: LPs paying, or subject to, management fees or carried interest. GPs may define the population differently and are asked to disclose their definition.
4. Inputs and source types
4.1 Inputs. A figure that can be recalculated needs:
- dated contributions, each dated when cash moved: for a capital call, the due date rather than the notice date, as the ILPA Performance Template guidance specifies;
- dated distributions with their type (return of capital, income, gain; recallable or not; cash or in kind);
- NAV with its as-of date;
- commitment, currency and the investor population;
- for portfolio-level gross figures, the dated cost and proceeds of each investment.
A figure for which these are unavailable can be reported with its source; it cannot be recalculated.
4.2 Sources. Each reported figure is recorded with its evidence origin, as defined in the Evidence & Provenance Standard:
| Source | Evidence origin | What the figure usually is |
|---|---|---|
| The manager's own published statements or advertisements | DISCLOSED | Fund-level or portfolio-level, gross and net; for advisers registered or required to be registered with the SEC, advertisements are subject to the US Marketing Rule |
| Quarterly reports, capital account statements and ILPA templates, obtained from the manager | DISCLOSED | Fund-level and portfolio-level figures with cash-flow detail |
| Performance reports in public pension board or investment committee materials | OFFICIAL_INSTITUTIONAL | LP-specific net figures on that investor's commitment |
| News reports and third-party articles | OSINT_SOURCED | A restatement; traced to its origin before use |
| Licensed datasets | LICENSED_THIRD_PARTY | As defined by the licensor |
4.3 Derivation status. A figure stated by its source is OBSERVED and is kept exactly as stated, with the reporter's own qualifiers. A figure Altss computes from observed components (a TVPI from paid-in, distributions and NAV; a pooled IRR from dated flows) is DERIVED and records its inputs and the rule used. A figure computed with an estimated NAV or estimated cash-flow dates is ESTIMATED. A recalculation never overwrites the reported figure.
4.4 Unusable figures. A performance figure with no as-of date, no gross or net basis and no identifiable reporter may be recorded as a claim of its publisher. It is not used as an input to any derived figure or comparison.
5. Method
5.1 IRR is money-weighted. IRR, net IRR and gross IRR are never described as time-weighted. Because IRR reflects the timing and size of cash flows, anything that moves cash-flow dates (a subscription facility, an early partial exit, a dividend recapitalisation) changes it without changing the value created.
5.2 Date-exact calculation. IRR is computed on actual cash-flow dates (XIRR): each flow is discounted by (date − first date) / 365 years. Dated flows are not treated as equally spaced periods. GIPS 2020 requires money-weighted returns to use daily external cash flows for periods from 1 January 2020 (provision 2.A.29(b)).
5.3 NAV as terminal value. An interim IRR includes the NAV as a positive cash flow on its as-of date, as if distributed on that date. The figure is labelled INTERIM with the NAV date. A figure computed on distributed cash only, without NAV, is labelled REALISED-ONLY and is not compared with interim IRRs. When the fund has distributed all value, the IRR is FINAL.
5.4 Annualisation. Since-inception IRR is annualised. A return for a period shorter than one year is not annualised (GIPS 2020, 2.A.12): for a fund less than a year old, the cumulative return is shown unannualised or the figure is marked not meaningful.
5.5 Multiples. TVPI, DPI and RVPI share one paid-in denominator and one as-of date. Paid-in includes capital called for fees and expenses. MOIC is computed on invested capital and is gross unless its inputs are net. A MOIC is never relabelled as a TVPI, or the reverse.
5.6 Gross and net. Every return and multiple carries GROSS or NET.
- NET is after all fees, expenses and carried interest borne by the stated investor population. This matches the US Marketing Rule definition of net performance: results after deducting all fees and expenses that a client or investor has paid or would have paid (17 CFR 275.206(4)-1(e)(10)).
- GROSS is before management fees, fund expenses and carried interest. Its method is stated: portfolio-level (fund-to-investment cash flows), or fund-level using the ILPA Granular methodology (calls classified by transaction type, so that calls for fees and expenses and carry are excluded) or the ILPA Gross Up methodology.
- Gross and net are compared only over the same period and with the same type of return and methodology, which is also what the Marketing Rule requires of an adviser that shows gross performance (17 CFR 275.206(4)-1(d)(1)).
5.7 Level and population. Each figure states its level: FUND (with its population, normally all fee-paying LPs), PORTFOLIO (REALISED, UNREALISED or TOTAL) or LP-SPECIFIC. An LP-specific net IRR reflects that investor's admission date, fee terms, side letters and currency. It is not presented as the fund's return.
5.8 Subscription facilities. Where a fund uses a subscription facility, each figure is labelled WITH, WITHOUT or UNSTATED.
- Figures with different labels are not compared with each other.
- A gross figure WITHOUT is never paired with a net figure WITH. In a Marketing Rule FAQ posted 6 February 2024, SEC staff stated their view that an adviser presenting gross IRR calculated without the impact of fund-level subscription facilities, compared only with net IRR calculated with that impact, would violate the US Marketing Rule. Staff FAQs state the staff's views; they are not rules and have no legal force.
- Where both figures are reported, both are shown.
- A WITHOUT series includes the facility cash flows: each contribution is dated when the facility was drawn for it (GIPS 2020, 2.A.50). Facility interest and fees may be kept or excluded; the GIPS Handbook permits either and recommends disclosing which. Altss states which treatment a derived figure uses, because the choice moves the result (Example 2).
5.9 Aggregation. A return for several funds or investments is a pooled figure, computed on their combined date-aligned cash flows plus the sum of their NAVs at a common as-of date. Pooled multiples sum numerators and denominators. An average of IRRs, simple or weighted, is not a portfolio return: if shown, it is labelled "average of fund IRRs" with its weights. Medians and quartiles describe a distribution of funds; they are not returns.
5.10 Since inception and horizon. Since inception is the default period. A horizon IRR from date A to date B treats the NAV at A as a contribution at A, the cash flows between A and B as they occurred, and the NAV at B as a distribution at B. It carries both dates. A horizon IRR is not compared with a since-inception IRR.
5.11 Comparison with public markets. A fund IRR is not compared directly with an index's time-weighted return. A comparison applies a public market equivalent method to the fund's own cash flows and names the method and the index: the Kaplan–Schoar PME, the Long–Nickels PME, PME+, the modified PME or Direct Alpha. GIPS 2020 requires a firm that presents a PME as a benchmark to disclose the index used (5.C.33). Method choice is governed by the Benchmarking Methodology.
5.12 Vintage year. Every peer comparison states its vintage-year convention. The GIPS 2020 glossary names two methods: the year of the vehicle's first drawdown or capital call from investors, or the year in which committed capital from outside investors is first closed and legally binding. Data providers use these and others. A vintage year recorded under one convention is never silently replaced by one under another; each is stored with its convention.
5.13 Non-unique IRR. If cash flows change sign more than once (recalled distributions, clawback payments, LP givebacks), the IRR may not be unique. The figure is flagged, the multiples and cash-flow series are shown, and a modified IRR or a net present value at a stated rate may be added as a labelled alternative.
5.14 Recallable distributions and recycling. Figures follow the capital account. The treatment of recallable distributions and recycled capital is stated. The ILPA Performance Template defaults are distributions net of carried interest and performance gross of recallable distributions; a GP using other treatments is asked to disclose them.
5.15 Currency. Figures are computed in the fund's reporting currency. A figure in an investor's currency states the currency and conversion method. A pooled figure across currencies converts each dated flow, not the end result.
5.16 Minimum label set. Every figure Altss displays carries: metric; GROSS or NET; level and population; WITH, WITHOUT or UNSTATED facility treatment; period (since inception from a stated date, or horizon with both dates); NAV as-of date; INTERIM, REALISED-ONLY or FINAL; currency; reporter and source; derivation status. A figure without a gross/net basis or an as-of date is not used in any comparison.
6. Calculation and classification rules
6.1 Formulas. CF are cash flows to the investor: contributions negative, distributions positive, NAV positive on its as-of date.
| Metric | Rule |
|---|---|
| XIRR | the rate r solving 0 = Σ CF_i / (1 + r)^((d_i − d_0) / 365) |
| DPI | D / PI |
| RVPI | NAV / PI |
| TVPI | (D + NAV) / PI = DPI + RVPI |
| PIC | PI / commitment |
| MOIC | (realised proceeds + unrealised value) / invested capital |
| Horizon IRR (A to B) | XIRR of: −NAV_A at A; flows in (A, B]; +NAV_B at B |
| Pooled IRR | XIRR of the date-by-date sum of members' flows, plus the sum of members' NAVs at a common date |
| Pooled TVPI | (ΣD + ΣNAV) / ΣPI |
Members of a pool must share a NAV date. Where they do not, member NAVs are rolled forward by adding later contributions and deducting later distributions, and the pooled figure is labelled ESTIMATED.
6.2 Label values.
| Qualifier | Values | When the source is silent |
|---|---|---|
| Basis | GROSS, NET | UNSTATED; excluded from comparisons |
| Level | FUND (population stated), PORTFOLIO (REALISED / UNREALISED / TOTAL), LP-SPECIFIC | UNSTATED |
| Facility | WITH, WITHOUT (interest kept or excluded), NO FACILITY, UNSTATED | UNSTATED |
| Period | SINCE INCEPTION (start date), HORIZON (start and end dates) | UNSTATED |
| Status | INTERIM (NAV date), REALISED-ONLY, FINAL | INTERIM if a NAV remains |
| Derivation | OBSERVED, DERIVED, ESTIMATED | as recorded under the Evidence & Provenance Standard |
6.3 Comparability test. Two figures are comparable only if metric, basis, level, facility treatment, period type, currency and date convention match and their as-of dates are the same or the difference is stated.
7. Conflict handling
7.1 Check that the difference is real. Before two figures for one fund are treated as conflicting, the following are checked in order:
- Vehicle. Same fund, not a parallel fund, feeder, alternative investment vehicle or continuation vehicle?
- Level and population. Fund-level against LP-specific is not a conflict. Three pension plans reporting three different net IRRs for the same fund at the same date are reporting three LP-specific results.
- Basis. Gross against net.
- Facility treatment. WITH against WITHOUT.
- Period and NAV date. Different as-of dates are two points in a series.
- Currency and date convention. A quarterly approximation against an XIRR on actual dates.
7.2 Reported against recalculated. If a figure recalculated from components differs from the reported figure by more than the reported figure's stated precision, both are kept: the reported figure as OBSERVED, the recalculation as DERIVED with its inputs. The difference is recorded. Neither overwrites the other.
7.3 Real conflict. Two figures with identical qualifiers and different values are marked CONFLICTING. Both remain visible with their sources. They are never averaged. Any preference between them follows the Source Reliability & Confidence Methodology.
7.4 Restatement. A restated NAV or corrected cash flow from the manager supersedes the earlier figure for the same as-of date. The earlier version is kept in the record's history.
8. Confidence and limitations
- An interim IRR or TVPI is only as reliable as the NAV inside it. The higher the RVPI share of TVPI, the more the figure depends on valuation. DPI is shown alongside because it contains no estimate.
- In a fund's early years, fees and expenses on small amounts of called capital usually produce low or negative returns (the J-curve). An early since-inception IRR is not evidence of manager skill.
- IRR can rise through timing alone. Phalippou (2008) describes how IRR distorts incentives around cash-flow timing and the grouping of funds, and biases averages upward.
- Once a fund has returned much of its capital, its since-inception IRR moves little, even if the remaining portfolio changes value.
- Multiples have no time dimension: a 2.0x TVPI earned over 3 years and over 12 years read the same.
- Gross portfolio-level returns exclude fees, expenses, carried interest and fund-level cash drag. Net portfolio-level figures derived by applying the fund-level gross-to-net ratio or spread, a method the ILPA Performance Template guidance describes, are synthetic and are labelled as such.
- A reported figure is the reporter's account. A manager's figure is self-reported; an LP's figure describes that LP's position.
9. Temporal rules
- The as-of date of an interim figure is its NAV date. It is not the report date, the publication date or the date Altss captured it.
- Reports arrive after their as-of date. The ILPA Performance Template guidance promotes, subject to each fund's governing documents, delivery within 60 days after each of the first three fiscal quarters and 120 days after fiscal year end for direct funds (funds of funds: 120 and 180 days; funds of funds of funds: 180 and 260 days). A figure first published in a given month usually describes a NAV from an earlier quarter.
- A figure with a later as-of date becomes the latest figure; earlier figures remain as a time series.
- A restatement is a new version of the figure for the same as-of date (rule 7.4).
- A vintage year is fixed under its convention once assigned (rule 5.12).
- Editions and effective dates of the references used here:
- GIPS 2020 Standards for Firms: effective 1 January 2020; required for GIPS Reports that include performance for periods ending on or after 31 December 2020.
- ILPA Reporting Template v2.0 (released 21 January 2025): applies on a go-forward basis to funds still in their investment period during Q1 2026 or commencing operations on or after 1 January 2026; first delivered for the Q1 2026 reporting period.
- ILPA Performance Template (released January 2025; v1.1 April 2025): for funds commencing operations on or after 1 January 2026, with data capture from Q1 2026 and first delivery four full fiscal quarters after commencement. ILPA's guidance suggests that a fund may be treated as commencing at its first drawdown from a subscription facility, its first capital call or the start of management fees, and defers to the fund's own definition.
- US Marketing Rule: compliance date 4 November 2022.
- The SEC Private Fund Adviser Rules adopted in August 2023, which included a quarterly statement requirement, were vacated by the Fifth Circuit on 5 June 2024 and are not in force.
10. Edge cases
- Fund younger than one year. No annualised IRR (rule 5.4).
- Fully written-off fund. NAV of zero is a held value, not a missing one; the IRR is computed on cash flows alone and may be −100% if nothing was distributed.
- Distributions in kind. Valued at the value used in the distribution notice on the distribution date; the treatment is stated.
- GP commitment, fee waivers and non-fee-paying investors. Excluded from fund-level net figures when the population is fee-paying LPs. ILPA notes that IRRs in financial statements may include non-fee-paying investors; the population is stated either way.
- Feeders, parallel funds and alternative investment vehicles. Combined as in the fund's financial statements, which the ILPA Performance Template guidance asks GPs to follow.
- Subsequent closes. Fund-level figures use the aggregated flows. An LP-specific figure for a later-close investor includes its equalisation payments as contributions.
- Secondary buyers. A buyer's IRR runs from its purchase price and date, not from the fund's inception, and is LP-specific.
- Continuation vehicles. A continuation vehicle has its own inception at the transfer value. The selling fund records the transfer as a realisation. A track record that links the two is labelled as linked.
- Clawback payments and LP givebacks. Recorded as negative flows on their dates; they may make IRR non-unique (rule 5.13).
- Distributions funded by borrowing. Where a NAV facility funds distributions, figures for that period are labelled, because DPI then includes borrowed cash.
- Open-end and evergreen vehicles. Time-weighted returns are the convention. GIPS 2020 permits money-weighted returns only where the firm controls external cash flows and the vehicle is closed-end, fixed-life, fixed-commitment or has illiquid investments as a significant part of its strategy (1.A.35). Altss does not place an evergreen fund's time-weighted return in an IRR peer comparison.
11. Worked examples
All amounts are illustrative, in USD millions. Values are computed with XIRR on actual dates, day count actual/365.
Example 1: interim net IRR and multiples. An LP population with commitments of 100 has these fund-level flows:
| Date | Flow | Type |
|---|---|---|
| 15 Mar 2022 | −40 | capital call (due date) |
| 30 Sep 2022 | −25 | capital call |
| 30 Jun 2023 | −20 | capital call |
| 31 Dec 2024 | +15 | distribution |
| 30 Sep 2025 | +30 | distribution |
| 30 Jun 2026 | +70 | NAV (terminal value) |
XIRR = 9.2%. Paid-in 85, distributions 45, NAV 70: TVPI 1.35x, DPI 0.53x, RVPI 0.82x, PIC 0.85. Treating the same six flows as equally spaced annual periods gives 8.5%, which is wrong for dated flows (rule 5.2). Labels: NET; FUND (fee-paying LPs); NO FACILITY; since inception from 15 March 2022; INTERIM, NAV 30 June 2026; USD; DERIVED.
Example 2: a subscription facility. The fund instead draws a facility for the first two investments (40 on 15 March 2022, 25 on 30 September 2022) and calls 68 from LPs on 15 March 2023: 65 to repay principal and 3 of interest and fees. Later flows are unchanged.
| Series | Contributions | IRR | TVPI |
|---|---|---|---|
| WITH facility | −68 (15 Mar 2023), −20 | 9.9% | 1.31x |
| WITHOUT, interest kept | −40, −25 on the draw dates; −3 on 15 Mar 2023; −20 | 8.1% | 1.31x |
| WITHOUT, interest excluded | −40, −25 on the draw dates; −20 | 9.2% | 1.35x |
Against the cost-consistent comparison (interest kept in both series), the facility raises IRR by about 1.8 percentage points while TVPI is unchanged at 1.31x; the 3 of facility cost is the reason TVPI is lower than in Example 1. Choosing to exclude interest from the WITHOUT series narrows the apparent effect to about 0.7 points. This is why rule 5.8 requires the treatment to be stated.
Example 3: gross and net. The fund invested 80 in portfolio companies. Realised proceeds are 50 and unrealised value is 80, so gross portfolio-level MOIC is (50 + 80) / 80 = 1.63x. Net TVPI from Example 1 is 1.35x. The gap has three parts in this example: 5 of the 85 paid in funded fees and expenses rather than investments; 5 of the 50 realised was retained for carried interest and expenses rather than distributed; and NAV of 70 is 10 below unrealised value of 80 because of accrued carried interest and fund liabilities. Showing 1.63x gross without the 1.35x net would breach rule 5.6.
Example 4: pooled IRR against average IRR. Fund A: −10 at year 0, +20 at year 2 (IRR 41.4%). Fund B: −100 at year 0, NAV 110 at year 3 (IRR 3.2%).
| Measure | Result |
|---|---|
| Simple average of IRRs | 22.3% |
| Commitment-weighted average of IRRs | 6.7% |
| Pooled IRR (combined flows −110, 0, +20, +110) | 6.1% |
| Pooled TVPI (130 / 110) | 1.18x |
Only the pooled figure is the return of the two funds held together (rule 5.9).
Example 5: horizon against since inception. For the fund in Example 1, NAV on 30 June 2024 was 95. The two-year horizon IRR to 30 June 2026 (−95 on 30 June 2024; +15; +30; +70 on 30 June 2026) is 12.7%, against a since-inception IRR of 9.2% at the same date. They answer different questions and are not ranked against each other (rule 5.10).
12. External references
| Reference | What this standard takes from it | Where this standard differs or adds |
|---|---|---|
| GIPS Standards for Firms 2020 (CFA Institute) | Money-weighted returns allowed only under 1.A.35; annualised since-inception MWR with daily external cash flows (2.A.29); no annualisation under one year (2.A.12); WITHOUT-facility returns include facility cash flows (2.A.50); with and without facility presentation, unless the line was repaid within 120 days from called capital and funded no distributions (5.A.2); TVPI, DPI, PIC and RVPI (5.A.4); labelling of gross/net and facility treatment (5.A.5); PME index disclosure (5.C.33); glossary definitions of money-weighted return, time-weighted return, PME and vintage year | GIPS binds firms that claim compliance. Altss applies the label set to figures from any source and records UNSTATED where a source says nothing |
| GIPS Standards Handbook for Firms | Interest on a facility may be excluded from WITHOUT returns, with disclosure recommended (discussion of 2.A.50) | Altss always states the treatment of any WITHOUT figure it derives |
| ILPA Performance Template, v1.1 (April 2025) | Fund-level net IRR and TVPI with and without facilities; optional fund-level gross; portfolio-level gross IRR and MOIC (realised, unrealised, total); Granular and Gross Up methodologies; cash flows dated when cash moved; fee-paying LP population; delivery timing | ILPA permits synthetic net portfolio-level figures; Altss labels them synthetic |
| ILPA Reporting Template v2.0 (January 2025) | Capital account, fees, expenses, offsets and carried interest: the components between gross and net | Fee terms themselves are covered in the Fund Terms & Alignment Framework |
| ILPA Principles 3.0 (June 2019) | Annual reports should set out IRR methodology, with net IRR on a levered and unlevered basis as best practice; IRR and TVPI or MOIC with and without facilities | — |
| ILPA, Enhancing Transparency Around Subscription Lines of Credit (June 2020) | Disclosures to monitor the effect of facilities on exposure and performance | — |
| SEC Marketing Rule, 17 CFR 275.206(4)-1, and staff FAQs | Gross only with net, equal prominence, same period, type of return and methodology ((d)(1)); net performance definition ((e)(10)); facility consistency (FAQ of 6 February 2024); extracted performance (FAQs of 19 March 2025) | Applies to advertisements by investment advisers registered or required to be registered with the SEC; the staff FAQs state staff views and have no legal force. Altss reference content is not an adviser advertisement; it adopts the gross/net pairing discipline as a general labelling rule |
| Private Fund Adviser Rules (2023) | Vacated 5 June 2024 (National Association of Private Fund Managers v. SEC, 5th Cir.) | Not relied on |
| Kaplan and Schoar (2005); Long and Nickels (1996); Gredil, Griffiths and Stucke (2023); Ljungqvist (2024) | Origins of the KS-PME, the Index Comparison Method behind the LN-PME, and Direct Alpha; review of PME methods | Method selection is left to the Benchmarking Methodology |
| Phalippou (2008) | Limitations of IRR as a performance measure | — |
13. Version and change log
- Version 1.0.0 (2026-10-01). First version of this standard. Replaces the content previously published at this address as "GP-LP Data Transparency Standards". Corrections relative to that page:
- IRR is stated as money-weighted; the earlier text called it time-weighted in three places.
- Vintage year: the two GIPS conventions are named and the convention must be stated, replacing the claim that one convention is universal.
- Gross and net: stated as a legal requirement for advertisements by advisers registered or required to be registered with the SEC, under the US Marketing Rule (compliance date 4 November 2022), not as an LP preference.
- Subscription facilities: with/without reporting is a GIPS requirement for GIPS reports and ILPA guidance; it is not a general legal mandate, and the SEC rule that would have required quarterly statements was vacated in June 2024.
- ILPA's Performance Template, Reporting Template and Principles 3.0 are named with versions and dates; they were previously presented as Altss analysis.
- All unsourced market statistics and all claims attributed to Altss data were removed. Material outside performance measurement (due diligence questionnaires, ESG reporting, LP-type expectations, regulatory calendar) was removed; due diligence material is covered by the Institutional LP Manager Due Diligence Framework.
- Version 1.1.0 (2026-10-01). Independent review. Corrected the description of the earlier page (it presented the US gross/net rule as an investor preference; it did not credit SEC rules to Altss); ILPA delivery windows described as a framework subject to fund documents; empty pinpoints filled. No change to rules, labels or worked examples.
- Version 1.2.0 (2026-10-02). Specialist review of the US legal and regulatory statements against their primary sources. The scope of the Marketing Rule is stated as advisers registered or required to be registered with the SEC (4.2, 12, 13), and the February 2024 staff FAQ on subscription facilities is quoted as a staff view without legal force (5.8). No change to rules, labels or worked examples.
Change control. Changes to the IRR conventions, the label set or the aggregation rules are major changes. New examples and clarifications are minor changes.
Concepts used
- Internal Rate of Return (IRR)
- XIRR (Date-Exact IRR)
- Net IRR
- Gross IRR
- Gross vs Net Returns
- Time-Weighted Return (TWR)
- Time-Weighted Return vs IRR
- Total Value to Paid-In (TVPI)
- Distributions to Paid-In (DPI)
- Residual Value to Paid-In (RVPI)
- Multiple on Invested Capital (MOIC)
- Pooled IRR
- Horizon IRR
- Subscription Line of Credit
- Vintage Year
- Public Market Equivalent (PME)
- Global Investment Performance Standards
- SEC Marketing Rule
- ILPA Reporting Template
- J-Curve
Sources
- Global Investment Performance Standards (GIPS) for Firms 2020. CFA Institute, 2020 edition; effective 1 January 2020; required for GIPS Reports with periods ending on or after 31 December 2020. Status: Current (checked 2026-10-01). Provisions 1.A.35, 2.A.12, 2.A.29 (incl. fn 17), 2.A.50, 5.A.1, 5.A.2, 5.A.4, 5.A.5, 5.C.33
- GIPS Standards for Firms 2020 - Glossary (defined terms). CFA Institute, Glossary section of the 2020 edition. Status: Current (checked 2026-10-01). Glossary: money-weighted return, time-weighted return, public market equivalent, vintage year
- GIPS Standards Handbook for Firms. CFA Institute, Handbook explaining the 2020 provisions (PDF dated 2021). Status: Current (checked 2026-10-01). Discussion of provision 2.A.50 (printed pp. 138-139)
- ILPA Performance Template (Granular Methodology and Gross Up Methodology), v1.1. Institutional Limited Partners Association, ILPA, Released January 2025 (QRSI); v1.1 April 2025. Status: Current; for funds commencing operations on or after 1 January 2026 (checked 2026-10-01). Granular Methodology guidance v1.1: Key Features (pp. 9-11), Overview (p. 12), Sections V-X (pp. 19-23), XIII (p. 25)
- ILPA Reporting Template (v. 2.0). Institutional Limited Partners Association, ILPA, v2.0 released 21 January 2025 under the Quarterly Reporting Standards Initiative (QRSI). Status: Current; ILPA recommends implementation from Q1 2026 (checked 2026-10-01). Suggested Guidance, Key Changes (p. 9) and applicability table
- ILPA Principles 3.0: Fostering Transparency, Governance and Alignment of Interests for General and Limited Partners. Institutional Limited Partners Association, ILPA, Third edition, released 27 June 2019. Status: Current edition (no 4.0 found as of 2026-10-01) (checked 2026-10-01). Financial Disclosures: Annual Reports (p. 34); Subscription Lines of Credit (p. 35)
- Enhancing Transparency Around Subscription Lines of Credit. Institutional Limited Partners Association, ILPA, June 2020 (follows the June 2017 guidance Subscription Lines of Credit and Alignment of Interests). Status: Current (checked 2026-10-01). Recommended disclosures
- 17 CFR 275.206(4)-1 - Investment adviser marketing (Marketing Rule). U.S. Securities and Exchange Commission (CFR text via eCFR; LII mirror), eCFR current as of 2026-09-29; last amended 2022-04-15 (later versions technical). Status: in force (checked 2026-10-01). 275.206(4)-1(a) introductory text; (d)(1); (e)(10)
- Marketing Compliance - Frequently Asked Questions. U.S. Securities and Exchange Commission, Division of Investment Management (staff), Last updated 2026-01-15. Status: current (staff views, not rules) (checked 2026-10-01). FAQ posted 2024-02-06 (gross and net calculated with the same methodology and time period; subscription facilities); FAQs posted 2025-03-19 (extracted performance); page preamble (staff views, no legal force)
- Investment Adviser Marketing (final rule), Release No. IA-5653. U.S. Securities and Exchange Commission, Adopted 2020-12-22; 86 FR 13024 (2021-03-05); effective 2021-05-04; compliance 2022-11-04. Status: in force (checked 2026-10-01). Final rule (86 FR 13024): DATES (effective 4 May 2021); section II.K (compliance date eighteen months after the effective date)
- Announcement Regarding the Private Fund Advisers Rules. U.S. Securities and Exchange Commission, 2024-10-31. Status: current (checked 2026-10-01). List of vacated rules incl. 211(h)(1)-2
- National Association of Private Fund Managers v. SEC, No. 23-60471 (5th Cir. June 5, 2024). U.S. Court of Appeals for the Fifth Circuit (via govinfo, USCOURTS collection), Decided 2024-06-05. Status: final (checked 2026-10-01). Decision of 5 June 2024
- The Hazards of Using IRR to Measure Performance: The Case of Private Equity. Ludovic Phalippou, SSRN (working paper), SSRN 1111796, 2008. Status: Working paper (checked 2026-10-01). SSRN working paper 1111796 (2008), main argument
- Private Equity Performance: Returns, Persistence, and Capital Flows. Steven N. Kaplan; Antoinette Schoar, The Journal of Finance, Vol. 60(4), pp. 1791-1823, August 2005. Status: Published (journal paywalled; NBER w9807 working paper) (checked 2026-10-01). Vol. 60(4), pp. 1791-1823, PME definition
- A Private Investment Benchmark. Austin M. Long III; Craig J. Nickels, AIMR Conference on Venture Capital Investing (University of Texas System), Dated 13 February 1996. Status: Conference paper (not peer-reviewed) (checked 2026-10-01). Index Comparison Method
- Benchmarking Private Equity: The Direct Alpha Method. Oleg R. Gredil; Barry Griffiths; Ruediger Stucke, Journal of Corporate Finance, Vol. 81, 102360, August 2023; SSRN working paper 2014 (doi:10.2139/ssrn.2403521). Status: Published (paywalled) (checked 2026-10-01). Vol. 81, 102360, Direct Alpha definition
- The Economics of Private Equity: A Critical Review. Alexander Ljungqvist, CFA Institute Research Foundation, Literature review, 2024. Status: Published (checked 2026-10-01). Section on PME
- Private Fund Advisers; Documentation of Registered Investment Adviser Compliance Reviews (final rule; technical amendments), 89 FR 91252. U.S. Securities and Exchange Commission (Federal Register via govinfo), Published and effective 2024-11-19. Status: in force (checked 2026-10-01). Background (Private Fund Adviser Rules adopted 23 August 2023; vacated by the Fifth Circuit; vacated amendments no longer in effect)
Related frameworks
Framework · Version 1.2.0
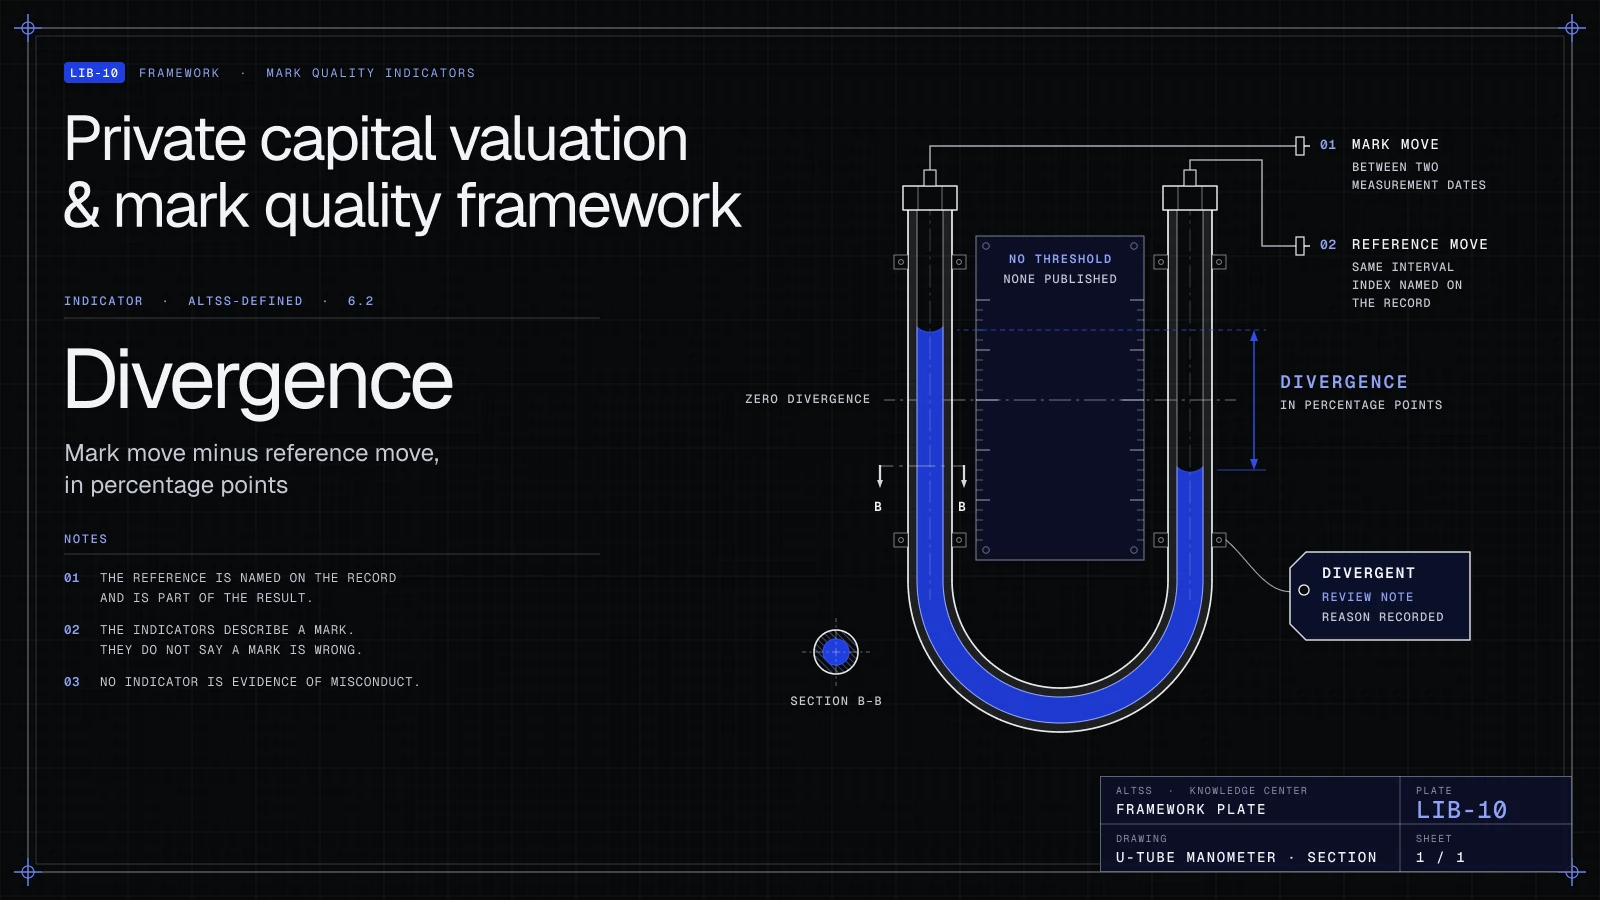
Private Capital Valuation & Mark Quality Framework
How unquoted private-capital investments and fund interests are marked to fair value under ASC 820, IFRS 13, the IPEV Guidelines (2025 edition) and Rule 2a-5, and the Altss-defined indicators used to read a mark: timeliness, staleness, divergence, dispersion and backtesting.
Framework · Version 1.1.0
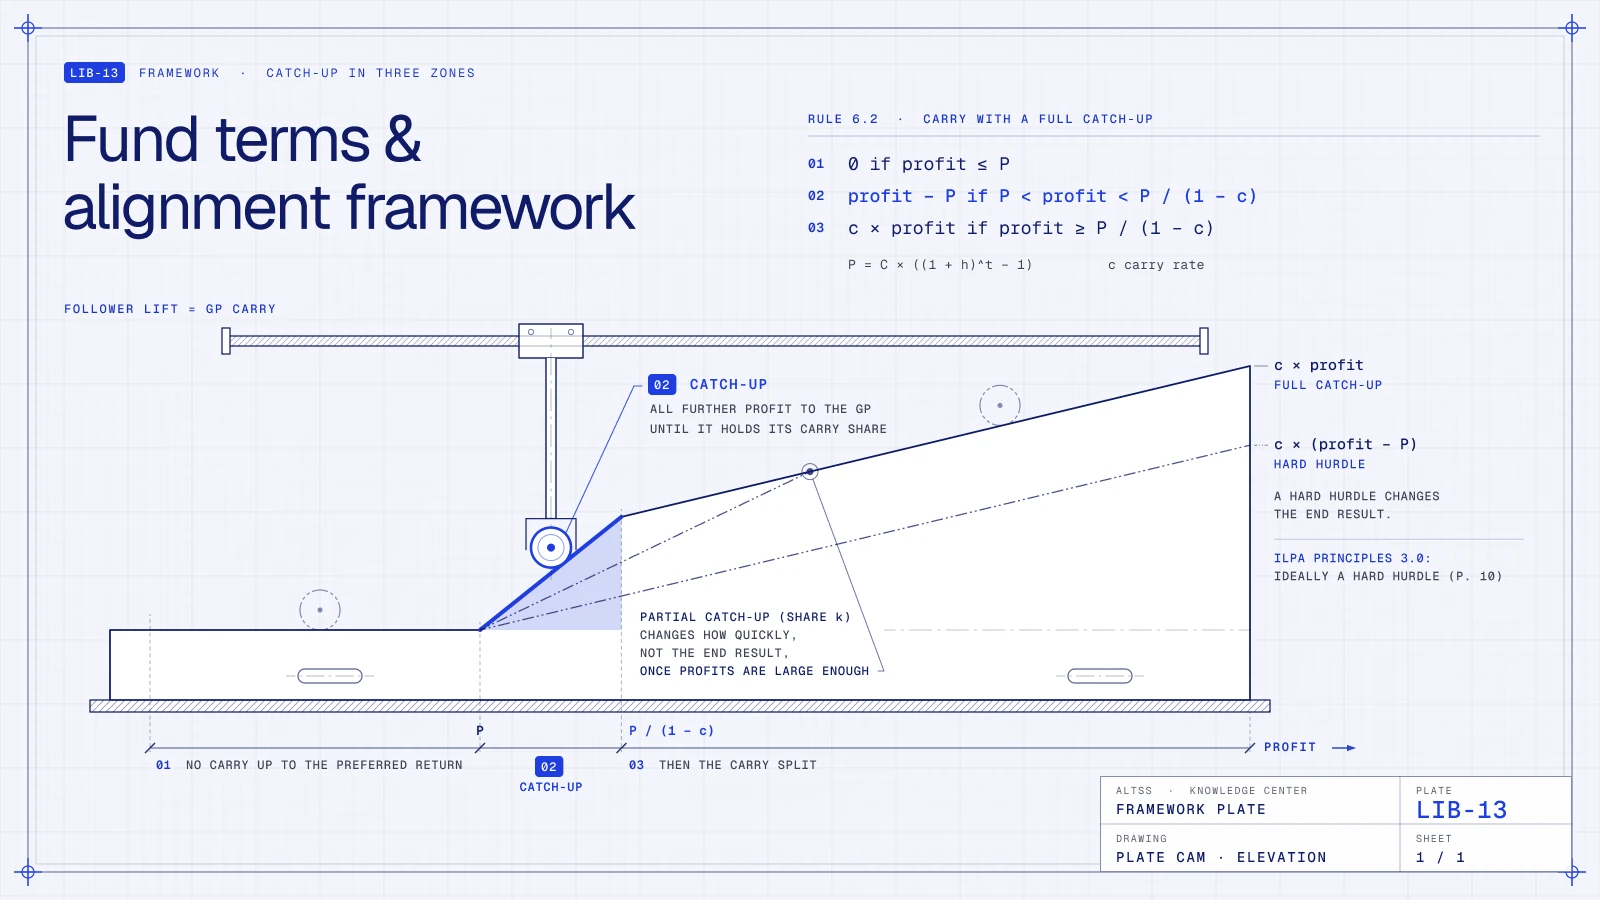
Fund Terms & Alignment Framework
A method for reviewing private fund terms: management fee base and step-downs, carried interest, preferred return, catch-up, whole-fund and deal-by-deal waterfalls, clawback, fee offsets, GP commitment and LP governance rights, with worked calculations and a mapping to ILPA Principles 3.0 and the Model LPA.
Standard · Version 1.2
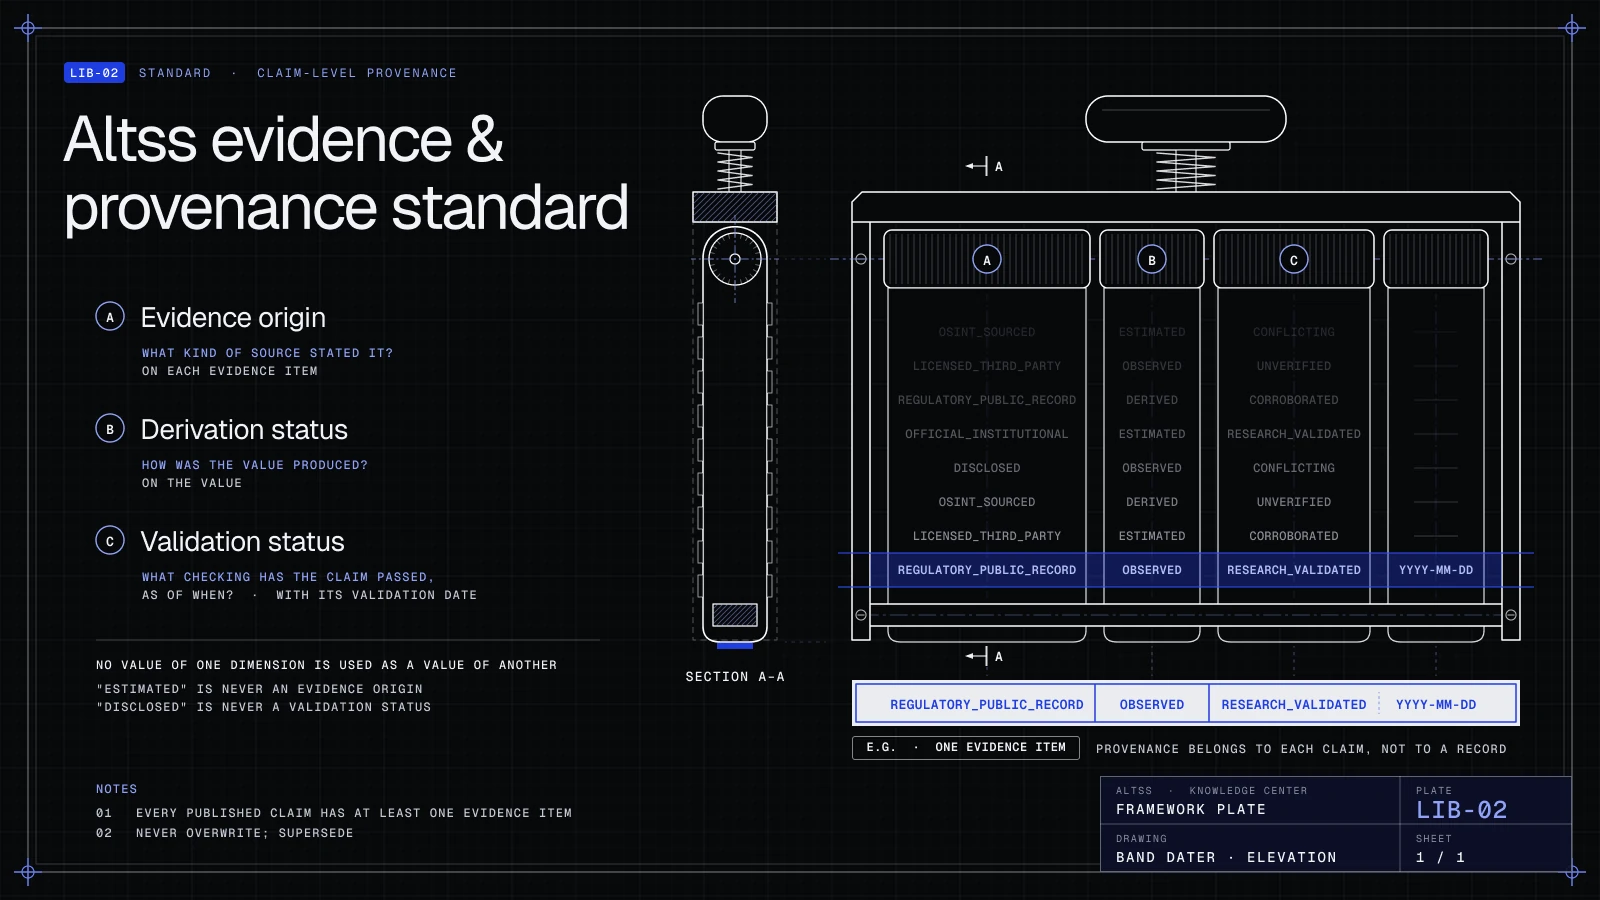
Altss Evidence & Provenance Standard
The Altss standard for recording evidence behind private-markets facts: claim-level provenance, evidence chains, three separate evidence dimensions (evidence origin, derivation status, validation status), distinct date types, null states such as unknown vs not disclosed, negative evidence, conflicts and claim citation.
Methodology · Version 1.2
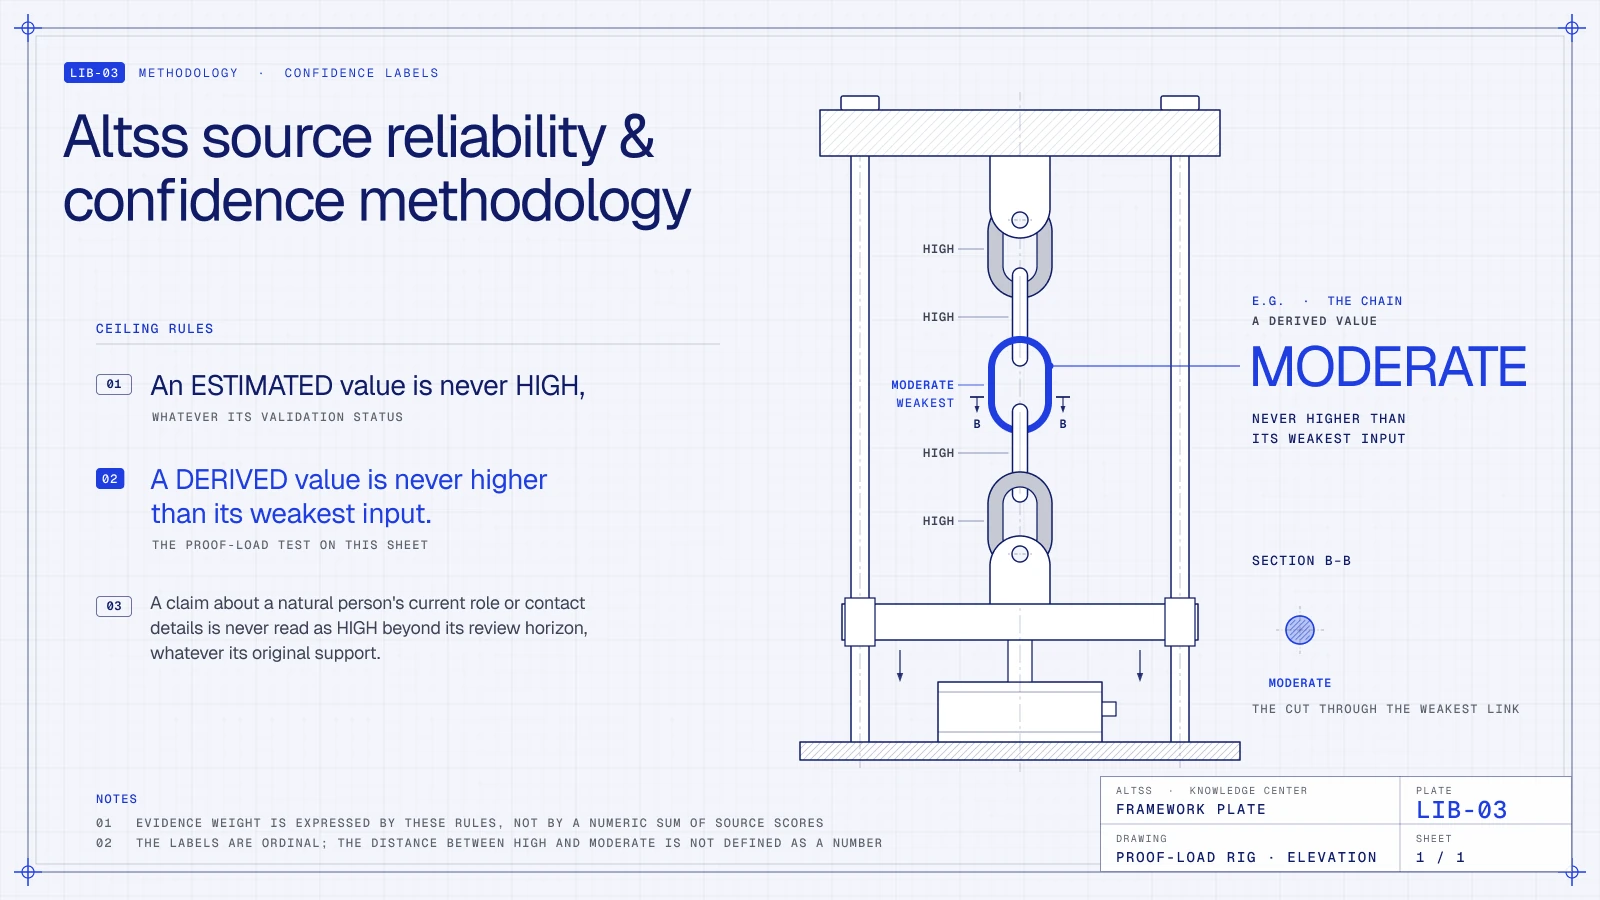
Altss Source Reliability & Confidence Methodology
The Altss methodology for grading sources and assigning confidence labels to private-markets claims: source authority classes, reliability and credibility grades adapted from the NATO Admiralty system, independence, use of validation status, conflict handling, label meaning and limits, calibration and decay.
Standard · Version 1.2
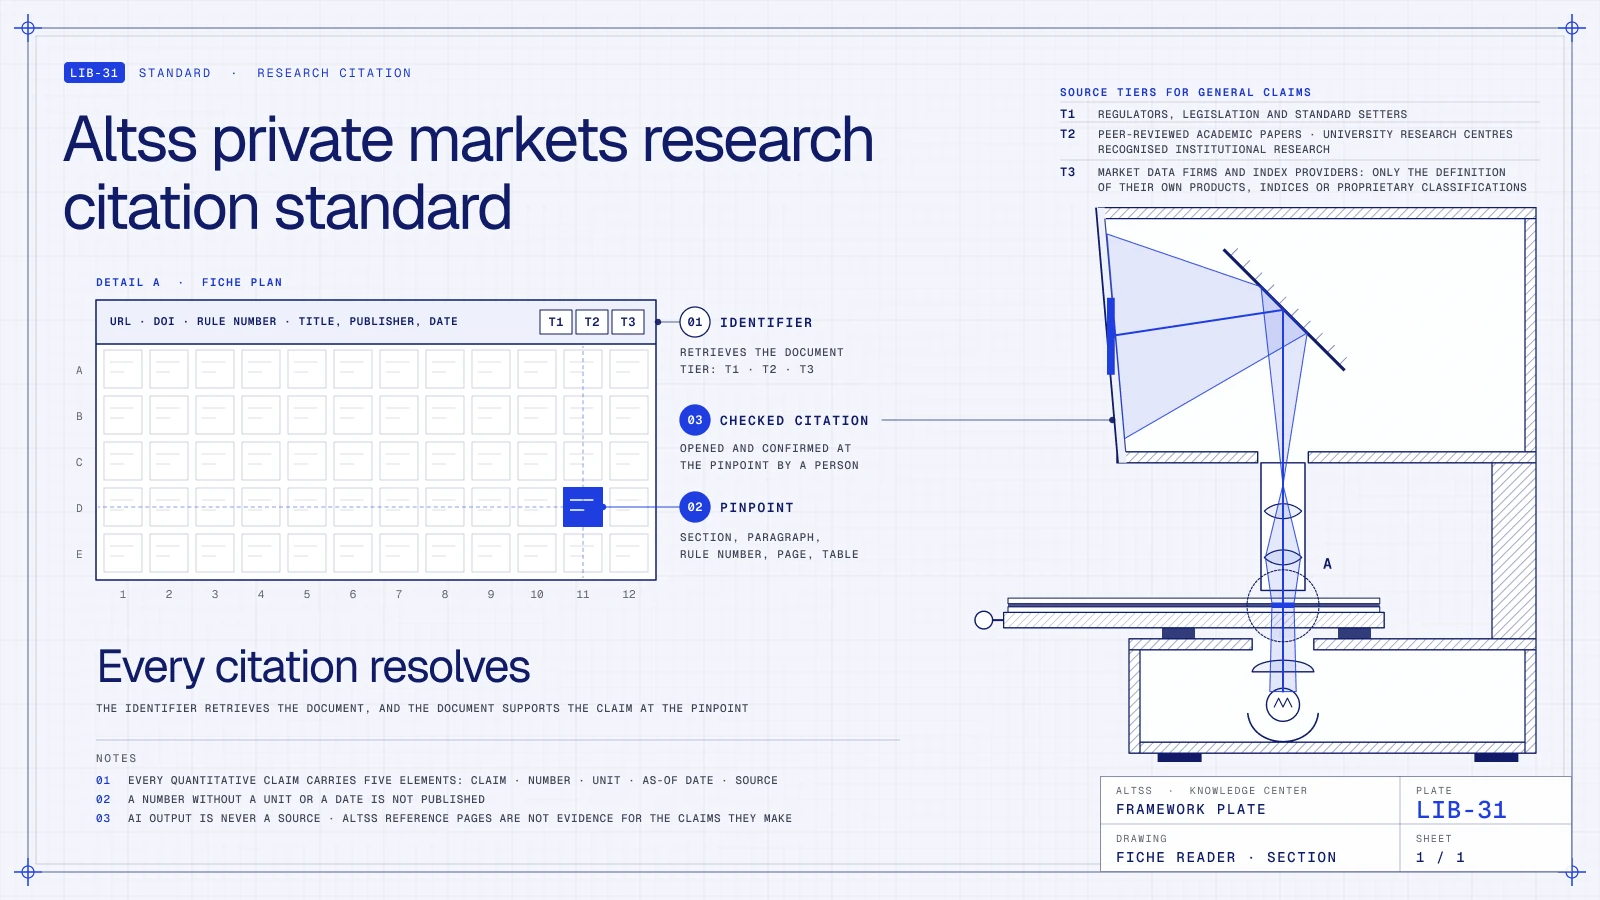
Altss Private Markets Research Citation Standard
Altss's rules for citing sources in private-markets reference and research content: source tiers, no self-citation or competitor evidence for general claims, a fixed claim format with unit and as-of date, recency markers, and rules for AI-assisted drafting.