Topic hub
Valuation
Valuation in private markets centres on fair value, whose accounting definition and source standards are set out in its own entry. For holdings without a quoted price, a reported value is an estimate, so the net asset value behind interim returns depends on valuation judgement. This hub covers the accounting standards and industry guidelines, the valuation techniques, and the practices that decide how reliable a reported mark is.
Sections run from standards, including the IPEV Valuation Guidelines, to techniques such as comparable company analysis, discounted cash flow and the EV/EBITDA multiple. Later sections cover methods for venture and complex capital structures such as the 409A valuation, and fund-level valuation, including return smoothing and secondary pricing.
Not in this hub: performance measures calculated from NAV, which are in Performance and benchmarking. Property-level inputs such as the cap rate are listed here and explained in Real estate.
Reference index
Definition:
Fair Value — Fair value is the price that would be received to sell an asset, or paid to transfer a liability, in an orderly transaction between market participants at the measurement date, as defined identically in US and international accounting standards.
Standards and value measures
2 concepts- IPEV Valuation Guidelines
The International Private Equity and Venture Capital (IPEV) Valuation Guidelines are best-practice recommendations, issued by the IPEV Board, for estimating the fair value of private capital investments and fund interests consistently with international and US fair value accounting standards.
- Enterprise Value (EV)
Enterprise value (EV) is the value of a company's operating business to all its capital providers: the value of its equity plus debt and other senior claims, minus the cash available to repay them.
Techniques
4 concepts- Comparable Company Analysis (Trading Comps)
Comparable company analysis is a relative valuation method that applies multiples of similar listed companies, such as enterprise value (EV) to EBITDA, to the subject company's own metrics, adjusted for differences in growth, risk and size.
- Discounted Cash Flow (DCF)
Discounted cash flow (DCF) analysis is a valuation method that sets an asset's value equal to the present value of its expected cash flows, discounted for timing and risk, including a terminal value for flows beyond the forecast period.
- EV/EBITDA Multiple
The enterprise value to EBITDA multiple (EV/EBITDA) is enterprise value divided by earnings before interest, taxes, depreciation and amortisation (EBITDA); it expresses a business's value as a multiple of its operating earnings and is commonly used to price buyouts.
- Cap Rate (Capitalization Rate)
The capitalization rate (cap rate) is a property's net operating income divided by its value or sale price; it expresses price as an income yield and is used to value income-producing real estate and compare pricing across assets.
Venture and complex capital structures
3 concepts- Pre-Money and Post-Money Valuation
Pre-money valuation is the value a financing round places on a company's existing fully diluted equity before the new money; post-money valuation adds the new investment and equals the round price per share times all shares afterward.
- Down Round
A down round is a financing in which a company sells shares at a lower price per share than it charged in its previous round.
- 409A Valuation
A 409A valuation is an appraisal of the fair market value of a private company's common stock, used in the US to set option exercise prices so the options fall outside Internal Revenue Code section 409A.
Fund-level valuation
2 concepts- Net Asset Value (NAV)
Net asset value (NAV) is the value of a fund's assets, measured at fair value, minus its liabilities; for a closed-end private fund it equals total partners' capital, and open-end vehicles also express it per share or unit.
- Secondary Pricing
Secondary pricing is the convention of quoting a private fund interest's price as a percentage of its NAV at a stated reference date, adjusted for cash flows to closing, with the unfunded commitment assumed separately by the buyer.
Valuation and returns
1 conceptMethodologies and frameworks
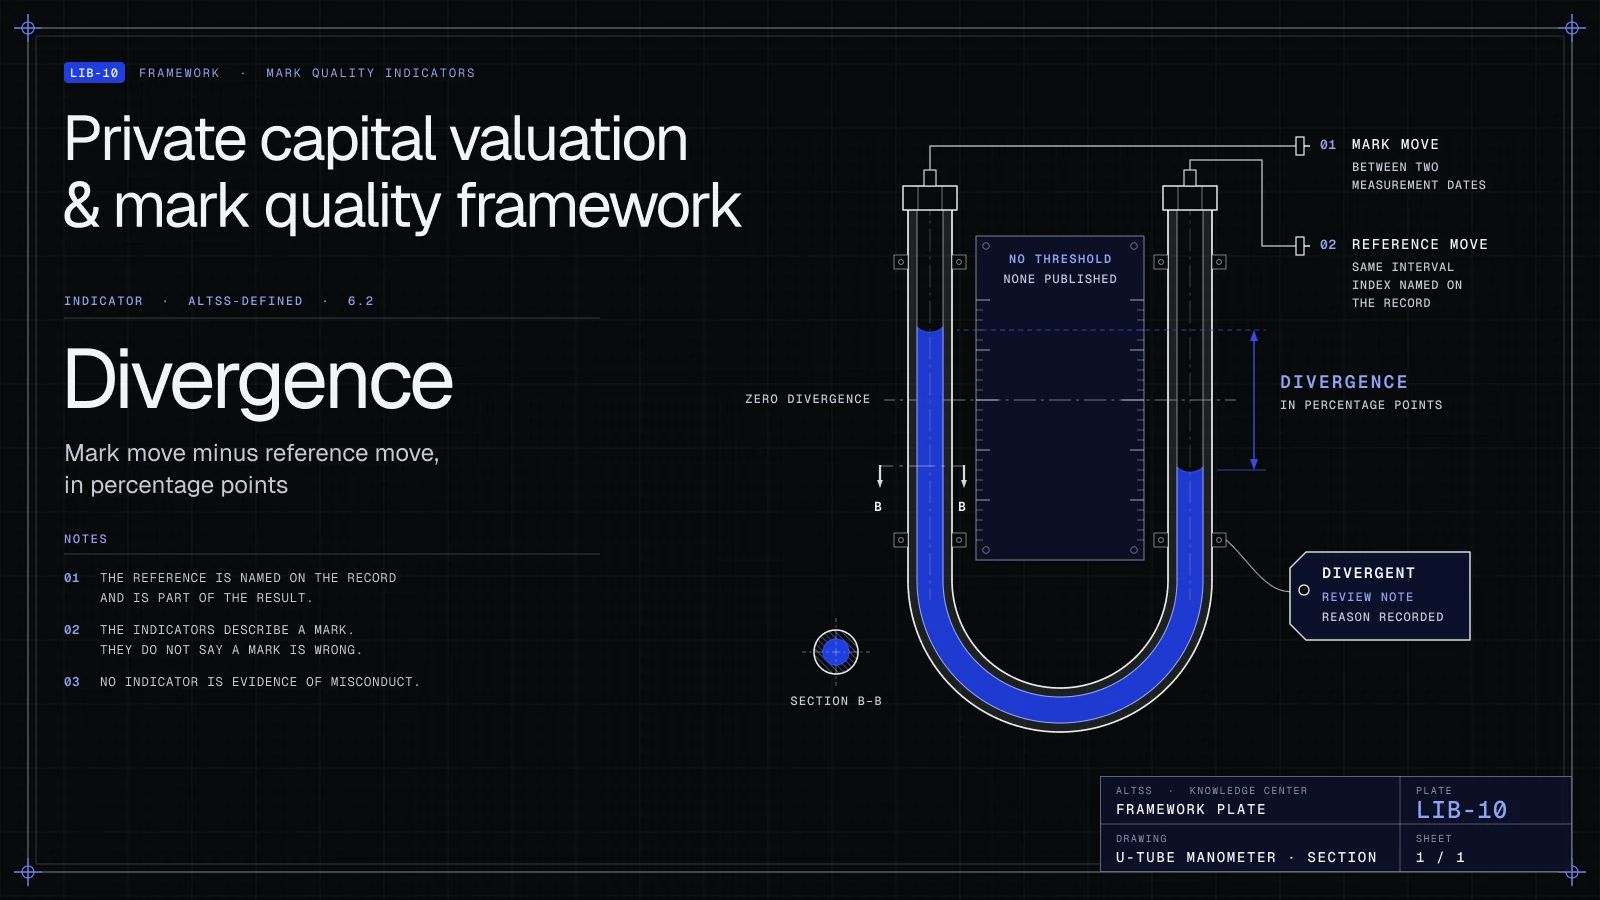
Framework · Version 1.2.0
Private Capital Valuation & Mark Quality Framework
How unquoted private-capital investments and fund interests are marked to fair value under ASC 820, IFRS 13, the IPEV Guidelines (2025 edition) and Rule 2a-5, and the Altss-defined indicators used to read a mark: timeliness, staleness, divergence, dispersion and backtesting.